
What 7 Key Market Indicators Are Telling Investors Right Now
US equity valuations have retreated from their recent highs, but all 7 major market indicators remain above their long-term averages.
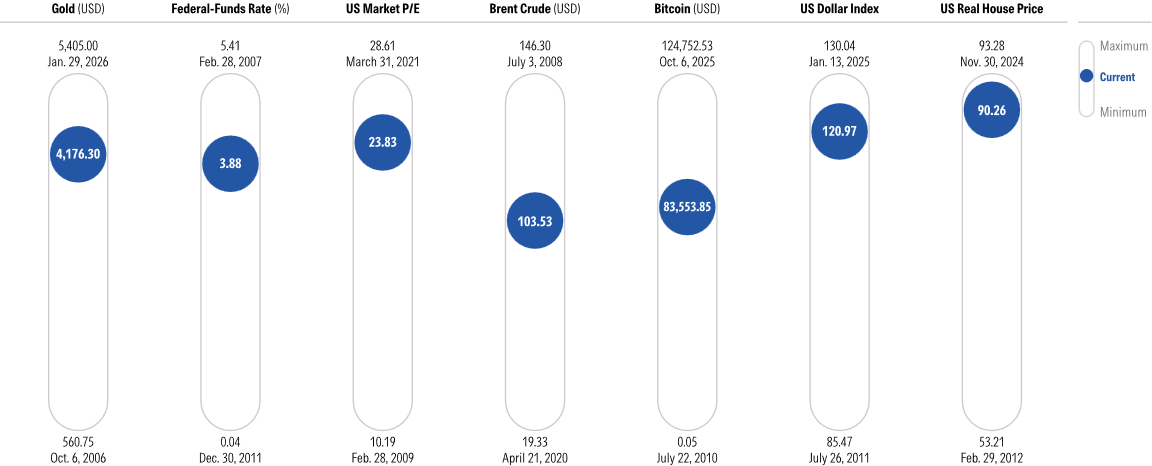
One of my favorite pieces of research is the quarterly Morningstar Markets Observer, which offers a wealth of information from a big-picture perspective. Particularly interesting is the report’s “Market Thermometer” chart, which shows seven key metrics and where each one stands relative to its range over the past 20 years.
I like this chart because it packs in so much information; even without reading all the details, you can get a quick picture of where major asset-class prices stand. Overall, the picture looks less alarming than it did earlier this year. All seven assets we measured are still trading above average compared with their historical ranges over the past two decades.
Market Thermometer
Gold Prices Remain High Despite Pullback
Current level: Above average.
What it means: Gold has fallen below peak levels, but the price remains relatively high.
Gold has had a strong run in recent years. After a 25% runup in 2024, it surged by nearly 70% in 2025. By the end of January 2026, it reached a peak of more than $5,400 per ounce. This performance was partly driven by central banks around the world buying up gold as they “de-dollarize” their reserve assets, as well as other investors seeking a safe haven amid macroeconomic turmoil and geopolitical uncertainty.
Since then, though, gold prices have fallen a bit, partly reflecting market expectations for higher yields on bonds and a stronger US dollar. By the end of September, gold was priced at about $4,261 per ounce—nearly 25% below its earlier peak.
Despite this decline, gold is still trading at a relatively high level, suggesting caution may still be warranted. As academic researchers Campbell Harvey and Claude Erb have found, there’s some evidence that gold prices tend to revert to the mean over longer periods. When gold is trading at elevated prices in inflation-adjusted terms, prices have often declined in subsequent periods. That happened in 1980, when steep prices were followed by a long period of sluggish returns during most of the following decade. The same pattern showed up when the real price of gold reached a peak in August 2011, which was followed by a sharp downturn from 2013 through 2015.
In short, while gold is more attractively priced than it was six months ago, it still carries a fair amount of downside risk.
Interest Rates Remain Above Their Historical Average
Current level: Above average.
What it means: In the wake of the Federal Reserve Open Market Committee’s 25-basis-point rate hike on Sept. 16, yields on cash remain slightly above inflation, making short-term fixed-income securities relatively attractive.
The midpoint of the target range for the federal-funds rate stood at about 3.87% as of Sept. 30 (the date for all of the data above), down from a high of 5.33% in 2024. However, the fed-funds rate remains significantly higher than its low of 0.04% as of late 2011, when the Federal Reserve’s zero interest rate policy reached its nadir. ZIRP and successive rounds of quantitative easing led to a nearly 15-year period of low borrowing costs.
Starting in March 2022, ZIRP became a distant memory as the Fed embarked on a series of aggressive interest rate hikes to tamp down inflation. But even now that the pace of rate hikes has slowed, yields on cash and short-term securities remain relatively attractive. For example, the three-month Treasury bill yield of 4.03% as of Sept. 30, 2026, remains slightly higher than the most recent annual inflation rate of 3.7%. As a result, investors saving for short-term goals don’t need to worry about the value of their savings eroding over time, at least for the moment.
More broadly, yields on high-quality fixed-income securities remain significantly higher than they were a few years ago. When rates were extremely low, there was nowhere for yields to go but higher and nowhere for bond prices to go but lower. Now we’re clearly in a different environment, making bonds more attractive than they were a decade ago.
US Stock Market Valuations Remain Elevated Despite Strong Earnings Growth
Current level: Above average.
What it means: Domestic stocks are still priced at relatively steep levels, but robust earnings growth has helped valuations trend a bit lower.
Domestic equities have continued to power ahead, with price gains driven by growth in corporate earnings as well as multiple expansion. As a result, the overall price/earnings ratio for the Morningstar US Market Index has more than doubled from its low of 10.19 in the wake of the global financial crisis.
Even so, the benchmark’s P/E of 23.83 as of Sept. 30, 2026, has drifted lower compared with its peak of 28.61 in March 2021. The reason? While most of the large-cap stocks that dominate the index have continued to post decent gains, earnings growth has remained in the neighborhood of 25% or more year over year. With a bigger denominator in the P/E equation, the overall number ends up lower.
That said, the overall market’s P/E remains on the higher end of its range over the past 20 years. Equity valuations could remain elevated if corporate earnings continue to deliver, but high prices also mean stocks have more room to fall if growth falls short of expectations. And now that valuations have already climbed higher, there’s not as much room for future multiple expansion as a driver of equity market returns.
While the US market as a whole isn’t in the bargain bin, there are still some pockets of value available for price-conscious investors. Valuations for international stocks, in particular, remain lower than those of their domestic counterparts, despite the strong gains in non-US stocks in both 2025 and 2026.
Oil Prices Have Risen Sharply
Current level: Above average.
What it means: A small position in a broad-based commodities fund that includes energy exposure can still make sense as a hedge against ongoing inflation, but valuations are less attractive than they were earlier this year.
The price of oil has been subject to dramatic highs and lows over the past 20 years. At the beginning of the period, prices surged, driven by growing demand from China and other emerging markets, combined with limited supply. As a result, prices reached a peak of about $146 per barrel in July 2008. That was followed by a precipitous drop during the global financial crisis, when the price dropped by more than 50%. Prices partially recovered over the next few years, only to suffer sharp losses in 2014 and 2015 as the OPEC group of major oil-exporting countries kept production levels high, leading to a glut in supply. Fast forward to the pandemic, and oil prices reached a low of $19.33 per barrel in April 2020.
Since then, oil prices have significantly increased, thanks mainly to the Iran war and supply disruptions stemming from blockades in the Strait of Hormuz. As a result, Brent crude prices were up about 70% for the year to date through Sept. 30, 2026.
Although oil prices are likely to remain volatile and would likely suffer in the event of an economic slowdown, a small stake in a broad-based commodities fund that includes exposure to energy could help improve portfolio diversification and hedge against inflation for investors who can tolerate risk.
Bitcoin Prices Have Rebounded but Remain Below Their Peak
Current level: Above average.
What it means: Although bitcoin remains well below its peak level, a runup in the third quarter makes it less attractive than it was earlier this year.
After hitting triple-digit returns in both 2023 and 2024, bitcoin reached a peak of about $125,000 per coin in October 2025. By June 2026, it was trading at less than half of that level.
As my colleague Valerio Baselli outlined in a recent article, concerns about ballooning levels of US debt, inflows into exchange-traded funds, and a weaker dollar have helped boost bitcoin prices in recent months. The price of bitcoin was up about 25% in the third quarter of 2026. Hypothetically, a more dovish Fed (after the one additional rate hike the market is currently expecting in December), easing inflation pressures, and lower real interest rates in 2027 and 2028 could provide ongoing support for bitcoin prices.
However, bitcoin prices are now on the higher end of their range over the past 20 years. In addition, the Digital Asset Market Clarity Act failed to move ahead in a key procedural vote in the Senate a couple of weeks ago. The lack of regulatory clarity for bitcoin in the US is a negative that could limit future price gains.
In addition, potential buyers should still be mindful of bitcoin’s extreme price volatility. And while the digital asset has started to gain more credibility among institutional investors, it remains a speculative asset with price swings often driven by fear of missing out.
The US Dollar Remains Historically Elevated
Current level: Above average.
What it means: The dollar could weaken further over the next several years.
For years, the US dollar seemed unstoppable. The Nominal Broad U.S. Dollar Index hit a low of 85.47 in July 2011 and mostly continued marching upward over the next 15 years or so. Turmoil in other markets was one reason behind the dollar’s extended climb. As countries such as Greece, Italy, Portugal, and Spain grappled with unsustainable debt levels, investors fled euro-denominated assets and took refuge in the dollar.
Generally strong economic growth and rising corporate earnings in the US also bolstered the dollar, as did the greenback’s undisputed position as the world’s leading reserve currency.
That narrative has started to change. During 2025, the Nominal Broad U.S. Dollar Index dropped about 7%. However, the current index value of 120.97 remains at the high end of the dollar’s range over the past 20 years. Central banks around the world have been “de-dollarizing” their reserves by purchasing both gold and other currencies. The rising federal debt, which is equivalent to 125% of gross domestic product, could also weaken investor confidence and further decrease demand for dollar-based assets. Morningstar US Chief Economist Preston Caldwell expects the US Fed to resume a series of rate cuts in 2027 and 2028, which would be another factor depressing demand for dollar-based assets.
All of this makes it especially important to make sure your portfolio has some exposure to non-dollar-denominated assets. In addition to domestic equity exposure, most portfolios should include an international-stock fund that doesn’t hedge its currency exposure.
US Home Prices Remain Near Their Inflation-Adjusted Peak
Current level: Very high.
What it means: Retirees may have an opportunity to tap into home equity to help cover spending needs, while younger people may be priced out of homebuying.
After dropping for a few years in the wake of the global financial crisis, US home prices have mostly climbed higher in inflation-adjusted terms. Our customized benchmark of real (inflation-adjusted) housing prices hit a low of 53.21 in 2012 and is now close to its peak of 93.77.
While housing prices vary by location, many retirees may be sitting on hundreds of thousands of dollars in housing wealth. In the Chicago metropolitan area, for example, the median home is now priced at about $389,000, compared with as low as $160,000 in 2012. Retirees who don’t mind downsizing could sell an existing residence and move into a smaller place. Or they could use those proceeds to cover part of the costs for moving into a continuing-care retirement community.
Retirees who don’t want to relocate could also consider a home equity loan or home equity conversion mortgage, although both options can be pricey and complex.
On the other end of the spectrum, younger people might need to settle for a smaller fixer-upper or continue renting for a few more years while building up savings.
With 7% Mortgage Rates, Should You Rent or Buy?
Editor’s Note: A version of this article was published on Aug. 4, 2026.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States