
Want to Invest Beyond the US? Here Are 3 Top European Stocks to Consider
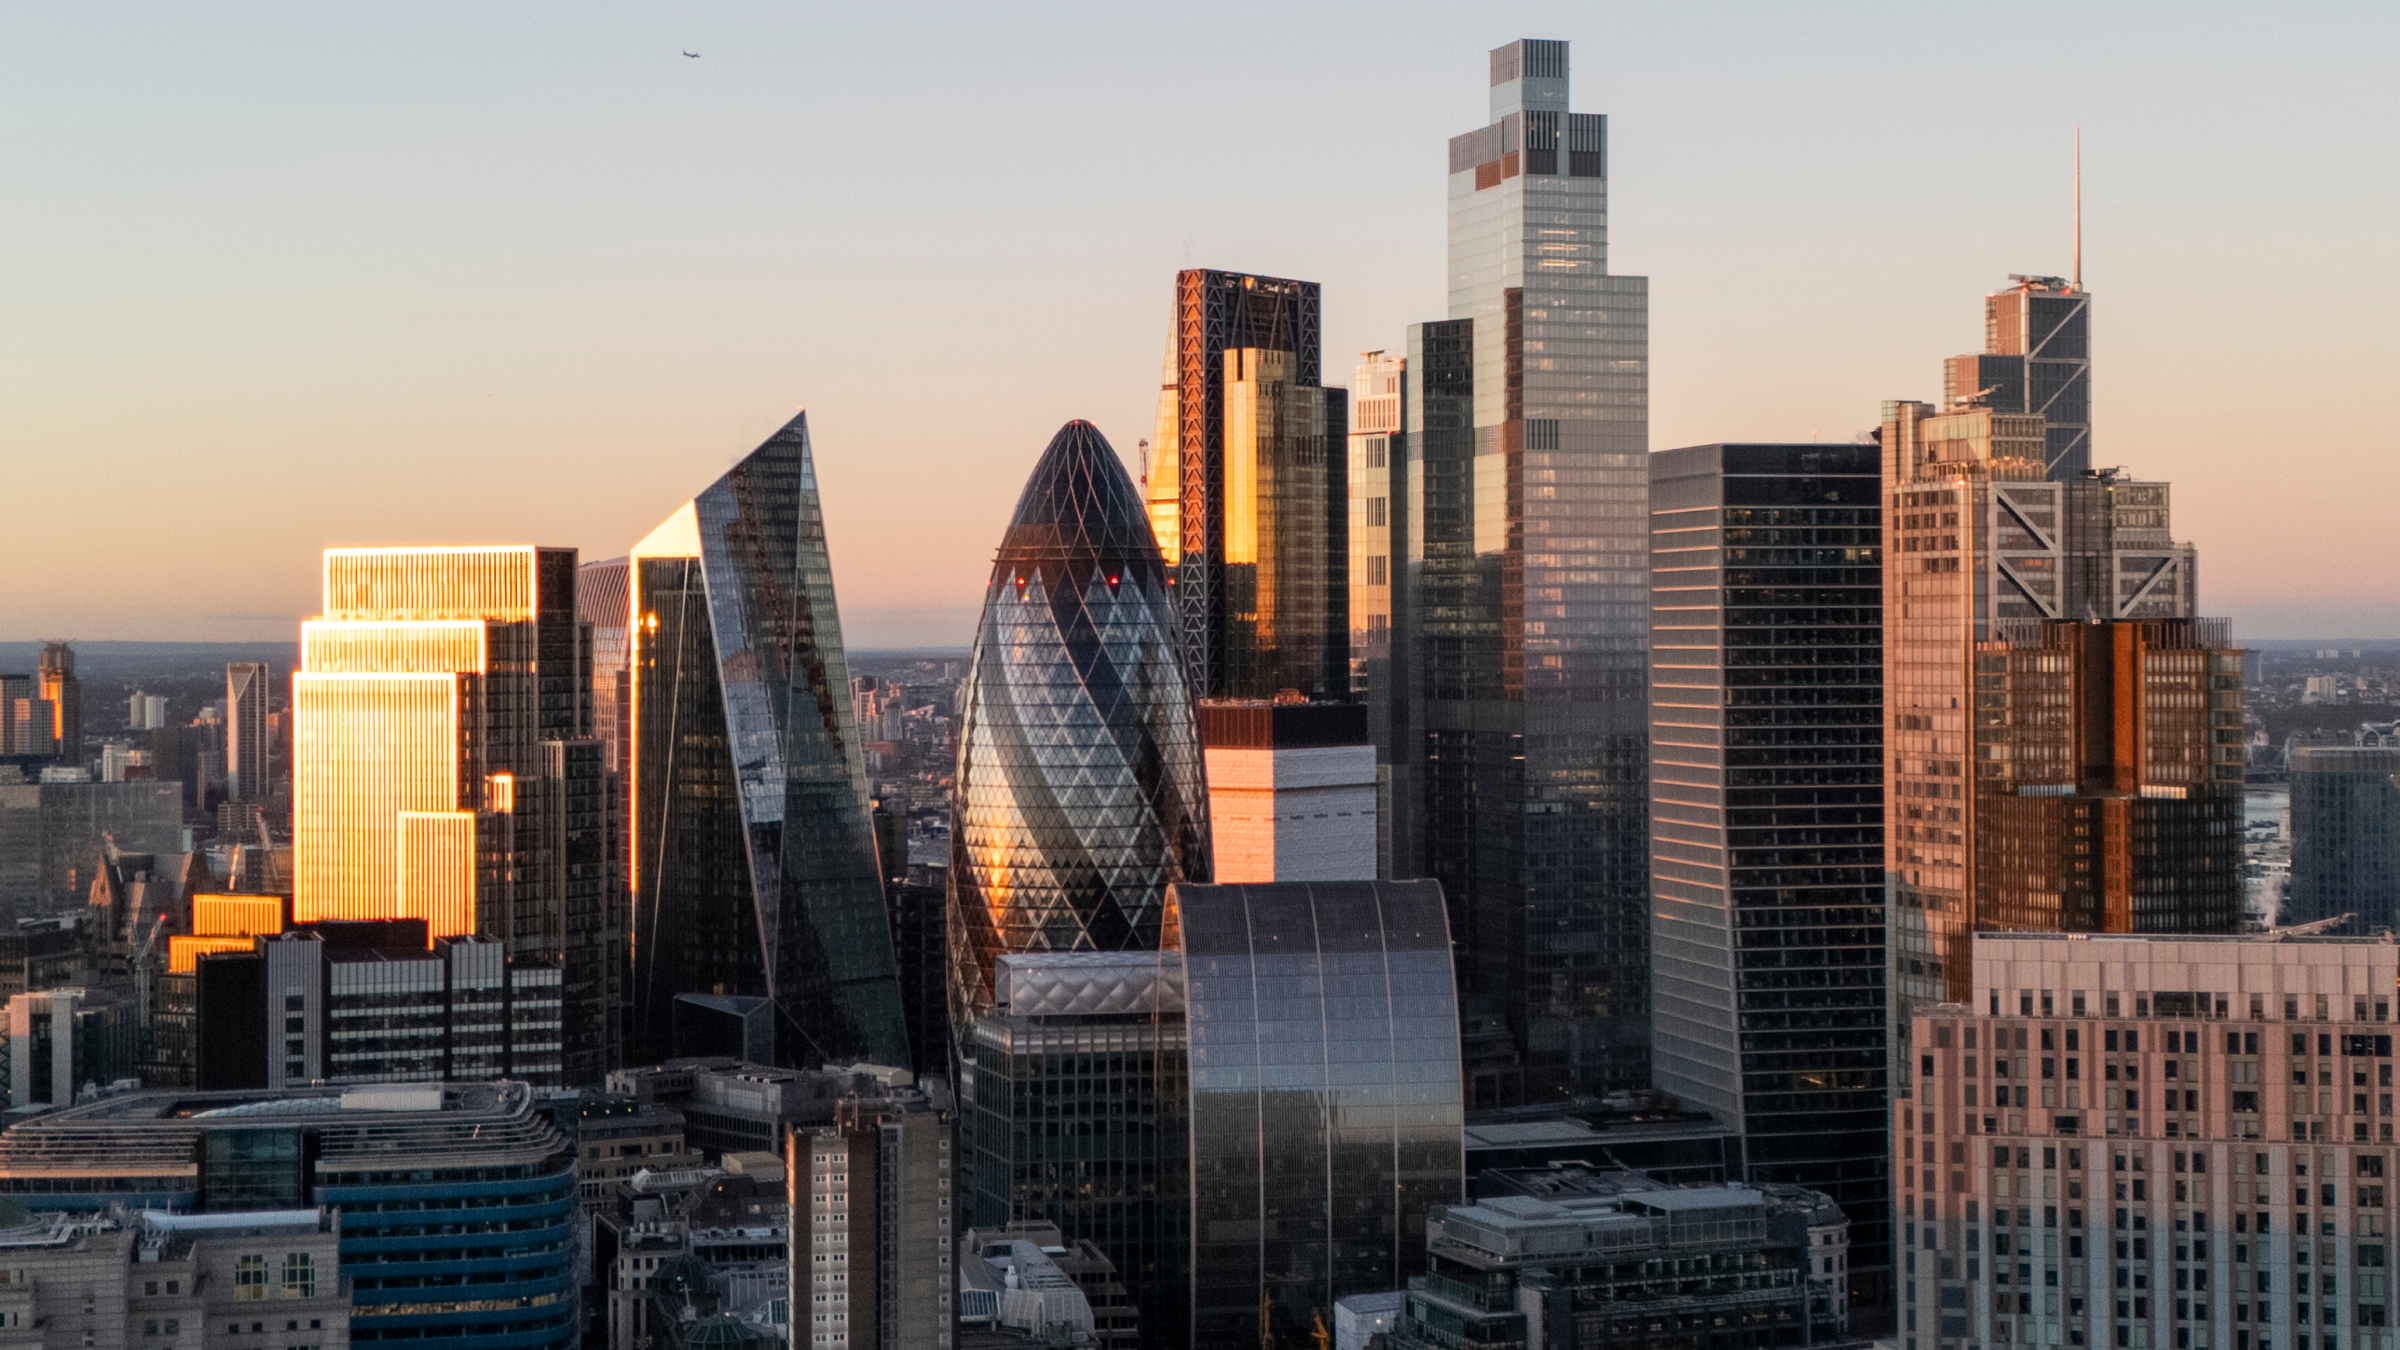
Despite AI-fueled gains driving US market outperformance, we see opportunities in these overlooked corners of Europe’s market.
On the Aug. 10, 2026, episode of The Morning Filter podcast, host Susan Dziubinski talks with Morningstar Europe’s Market Strategist Michael Field to discuss risks and opportunities in the international markets and his top picks. Here is an excerpt from the show.
Susan Dziubinski: Let’s talk about international markets. On paper, international stocks are outperforming US stocks this year, but that hasn’t been the case when you look specifically at Europe, right?
Michael Field: No, exactly right. I think some of those numbers for international stocks are distorted by some of the outperformance of emerging markets, for instance. But Europe has actually tracked the US reasonably closely, albeit slightly underperforming. Europe’s up something like 10.5% year to date versus around 12.5% for the US. Pretty good performances all around, I would say.
What’s Driving European Stock Market Performance?
Dziubinski: For sure. Let’s talk a little bit about what might be driving that performance up for European stocks. Does the difference boil down to, you mentioned emerging markets; is it really a developed- versus emerging-market story? Does it boil down to a sector story? Is it both, or is it something else entirely?
Field: I think there’s a lot of nuance on it. Unsurprisingly, given everything that’s happened this year with the Iran war, there are a lot of moving parts to the equation. I think artificial intelligence has been a huge element to this. We can’t have a conversation without mentioning AI, and this is one specific instance where indeed we cannot—AI stocks have been performing really well of late, and the US obviously has a high concentration and a high exposure to those big Magnificent Seven names (Alphabet, Amazon.com, Apple, Meta Platforms, Microsoft, Nvidia, and Tesla) and AI firms.
If I look at the Stoxx 600, the main European index for the past quarter, the biggest performers within that index have all been exposed to AI, be they semiconductor stocks or others, but they’ve all been exposed to that theme. I think one of the big differences why Europe has underperformed the US, albeit marginally, is that we don’t have that exposure to those Big Tech giants that you can get through the US market.
Is There a Valuation Gap Between European and US Stocks?
Dziubinski: Got it. Then, let’s talk a little bit about valuations today. How do European stocks look relative to US stocks from a valuation perspective? Is there a sizable valuation gap between the two or not really?
Field: I think this is what’s going to surprise people; if I look at valuations, given how well markets have performed, given how well the US has performed, you might expect that markets are trading at kind of large premiums given all this talk of bubbles as well that we hear, but that’s certainly not the case. The US market is actually more attractive on the face of it than Europe at the moment. It’s trading at something like a 10% discount to our fair value estimate, and then Europe’s trading at something like a 4% discount to our fair value estimate. Is there a huge amount of value there? Certainly not in Europe, I would say, but it’s not expensive. That number probably belies the underlying story that if I break it down into sectors, which I know we’re going to talk about in a minute, there are a lot of opportunities there and much more attractive opportunities within individual sectors.
Where Are the Opportunities in European Stocks?
Dziubinski: Let’s talk about some of the opportunities from a valuation perspective today in Europe. Let’s start, though, through the lens of market capitalization and style. Are large caps or small caps looking more attractive? More value-type stocks or growth-type stocks? Where’s the opportunity?
Field: I think it’s moved around an awful lot as well. I’m glad I update the numbers every now and again because the picture has changed dramatically in Europe. I think, until now, what I’ve been saying, or for the first couple of quarters of the year, is that small-cap stocks are really attractive in Europe, way more so than the US investors seem to have discovered a lot of those names or suddenly had a bit more faith in a lot of those names.
You’ve seen the valuations of small-cap stocks improve or disimprove from an investor’s perspective over the past number of months. They’re more expensive now. I think if I’m looking at opportunities in Europe right now, a lot of it’s in the mid-cap space and a lot of it’s still in the value space. Some of those value stocks, some of those stocks that don’t really have the same growth profile, are the ones that are now looking attractive in Europe.
Which European Sectors Look Attractive Today?
Dziubinski: Let’s pivot and move over to talk about sectors, which you alluded to, where there are some real opportunities. Talk a little bit about which sectors look particularly attractive. Talk about which ones maybe look particularly pricey. Also comment, Michael, on how the sector story, from a valuation perspective, differs in Europe than it does in the US.
Field: Certainly. Dealing with the most attractive first: Cheapest sectors in Europe right now, or the most attractive in our eyes, are certainly heavily weighted toward consumer. Both consumer cyclical and defensive sectors are the two cheapest in Europe at the moment, particularly the cyclical sector. It’s trading at something like a 16% discount to our fair value estimate. Despite the index as a whole being almost fairly valued, there’s still a very attractive opportunity within consumer cyclicals.
Consumer defensive is still trading at a reasonable discount, something like around 9%. We’ve seen catalysts for improvement in that sector. We’ve seen improvements in some of those kinds of staple firms. They’re seeing more volume growth and pricing growth over the last earnings season. That means you’re not buying into something that’s never going to recover. We’re already seeing signs of recovery in that sector.
Lastly, on the other cheap sector we see in Europe, or an attractive sector we see in Europe, is healthcare. It’s been a sector that has had a lot of overhangs for a while, most notably government regulation, fears around patents, things like this. What we’ve seen now over the last number of months is that there’s been a bit of a resurgence. Investors are starting to warm up to that sector again.
Once again, earnings season has been pretty positive for a lot of these firms, so we still see a lot of attractiveness. In terms of overvalued sectors or less attractive sectors, there’s not a huge disparity in valuation in Europe. There are not a whole lot of sectors that I see that are way overvalued that I’m going to tell you to stay away from. Even sectors that saw a huge run, like energy, are around fairly valued. Similarly with financials, maybe a few percentage points overvalued.
The only one that’s getting a little bit heated in Europe is tech. It’s trading at something like a 10% premium to our fair value estimate. At the same time, that’s still not in the territory that we’re getting worried at this point. And then, to your question about how it differs: A lot of the valuations correlate to some degree. I would say if you’re looking for areas of differentiation, consumer defensive, we spoke about being cheap, is actually a lot cheaper than the US.
One of the reasons is we don’t have the huge giants like Walmart WMT and companies like this with those high valuations that are dragging things above the average. The other one is in tech as well, tech in the US; because we’re quite bullish actually on the Magnificent Seven names and a lot of the AI names, we think there’s huge potential there for growth. They’re actually trading at cheaper valuations in the US than some of the tech names we have in Europe. It’s a very mixed picture.
Why International Investors Should Watch Geopolitical Volatility and Inflation
Dziubinski: Let’s broaden things out, Michael, and talk a little bit about what you think the main risks that US investors who are investing globally should have on their radars for the remainder of the year.
Field: I think it’s surprising to some degree. I mentioned valuations aren’t expensive, right? At the same time, given all the risks that we have in the world currently, I would not have expected equity markets to be as buoyant as they are. I would’ve expected investors to be a little more circumspect, a little bit more concerned about the dangers at hand. What we’re seeing is the risks that are still in the background—things like inflation, potential for interest rates to increase—those concerns are slowly fading, but I think it’s something that people should still have in the back of their minds. When this whole Iran war kicked off, we really thought that interest rates might rocket, have to rocket to make up for inflation, which we expected to go through the roof across the board.
And inflation hasn’t been that bad in the US or Europe, actually. In Europe, it’s only maybe 2.6%, 2.7% at the moment. In the US, it’s not much different. That’s quite positively surprising. But the danger is, the longer this crisis continues in Iran and in the Middle East, with the Strait of Hormuz being closed one week and open the next, the danger is the disruptive effect that’s going to have on the global economy will eventually take hold. Maybe inflation hits new highs as a result of that, and interest rates need to go up. I think investors can ignore it for a long time, but as soon as interest rates start going up, that’s when it starts damaging the economy and when we all need to worry a little bit. I’m not trying to sound the alarm bell right now, but it’s something to keep in the back of our minds to stop us getting carried away, essentially.
Top European Stock Picks
Dziubinski: Let’s get some stock ideas, some investment ideas from you today. Let’s talk about some undervalued stocks that you like that are easily accessible to US investors. What do you like?
Field: One thing US investors have looked to Europe for over the past year or two, and that’s not accessible in the same way in the US, is around defense stocks. One of the big stocks in Europe, Rheinmetall RNMBY, the German arms and defense manufacturer, has seen its stock price rise hugely over the past three or four years. It’s had a load of catalysts to do so. It’s been a major arms supplier for the Ukraine war, and the valuation and the share price rose as a result. Actually, what we’ve seen over the past six months is that the share price is pretty much halved from the highs. If you look at our fair value estimate at the moment, we think the share could actually almost double from here.
Despite the fact that there are some huge catalysts, despite the fact that European countries like Germany are going to take at least a decade just to restock the weapons they’ve already given to Ukraine, these shares, and specifically Rheinmetall RNMBY, still aren’t pricing in some of these upsides that we’re seeing. Yes, there’s a bit of a cloud of doubt by investors at the moment as to whether that increased government spending can come through from NATO nations and, in particular, European nations, but we still see huge upside there. That’s the first one on the list.
Second of all, then we’ve got RELX RELX, and it is an Anglo-Dutch company that’s based more or less in the software data side of these things. We wrote a report, if you’ve been following our reports of late, about the “SaaSpocalypse,” and we mentioned RELX RELX in this. We looked at the stock and decided, OK, it still very much has a moat. We think it’s going to do well. It’s got proprietary data. It operates in a huge number of different products like LexisNexis, which some people might be familiar with. It’s a pretty widespread product, and it falls under one of these categories within the software-as-a-service space that we don’t believe is going to be disrupted by AI or that embraces AI sufficiently as not to be disrupted. Yet, its share price has still seen a fall alongside a lot of other software companies in that space. We now see a lot of upside for that stock. We think it’s robust. We think the results are still showing that up. That’s the second name in our list.
The final name in our list is in the utility space, but it’s actually a very interesting utility in case you think I was going to pitch you a boring stock here. This is National Grid NGG, the UK firm that’s in charge of the electricity grid essentially in the UK. Why that’s interesting is one, that the robustness and the reliability of its revenue stream is extremely high. People pay taxes, and it goes directly to this.
But why there’s a bit of a growth element to this, or why we think it’s interesting, is that, in Europe, generally speaking, there’s been a huge refurbishment or commitment to refurbishing the national electricity grid to cope with the increase in renewable energy and how that’s going to have to shift as a result of this. What you’re seeing is a large investment by firms like National Grid NGG that already has a kind of guaranteed return on capital attached to it. The growth profile for this company, we think, is strongly attractive over the next number of years. Something that will be interesting, particularly for US investors, is that this is one of the companies that pays a dividend that’s covered by cash flows, and it’s a dividend yield of north of 4%. It’s very attractive for a number of different reasons.
Subscribe to The Morning Filter on Apple Podcasts, or wherever you get your podcasts, and keep up with the latest research from hosts Susan Dziubinski and David Sekera on Morningstar.com.
3 Stocks to Sell and 3 Stocks to Buy in August
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States