
4 Top US Travel Stock Picks
With opportunities in the travel industry, Carnival and Norwegian are among the most attractive names.
The post-pandemic travel boom remains in flight, with many consumers undeterred by inflation. But even against this positive backdrop, several key travel stocks trade at attractive prices.
Morningstar analysts Dan Wasiolek and Jaime M. Katz still see “compelling opportunities” for long-term investors. These four stocks are their top picks:
Travel Stock Performance
Travel Stock Outlook
It took time for the industry to heal from the damage done by the pandemic and subsequent surge in inflation. With inflation coming down over the past year and consistent consumer spending, demand has been high. Underlying that demand is remote work flexibility and “a human-ingrained desire to travel,” Katz and Wasiolek say.
In the background, leisure travel is “holding up well,” while business travel has shown nascent improvement. “We think demand tailwinds will help offset any potential macroeconomic concerns, barring a severe recession, which we see as unlikely,” Katz and Wasiolek explain. “While leisure and domestic road travel patterns have moderated, we think business and group trips, international visits, and leisure excursions by sea will now support leisure demand.”
Among hotels, first-quarter occupancy at operators covered by Morningstar was flat from a year earlier, representing 93% of 2019′s pre-pandemic occupancy.
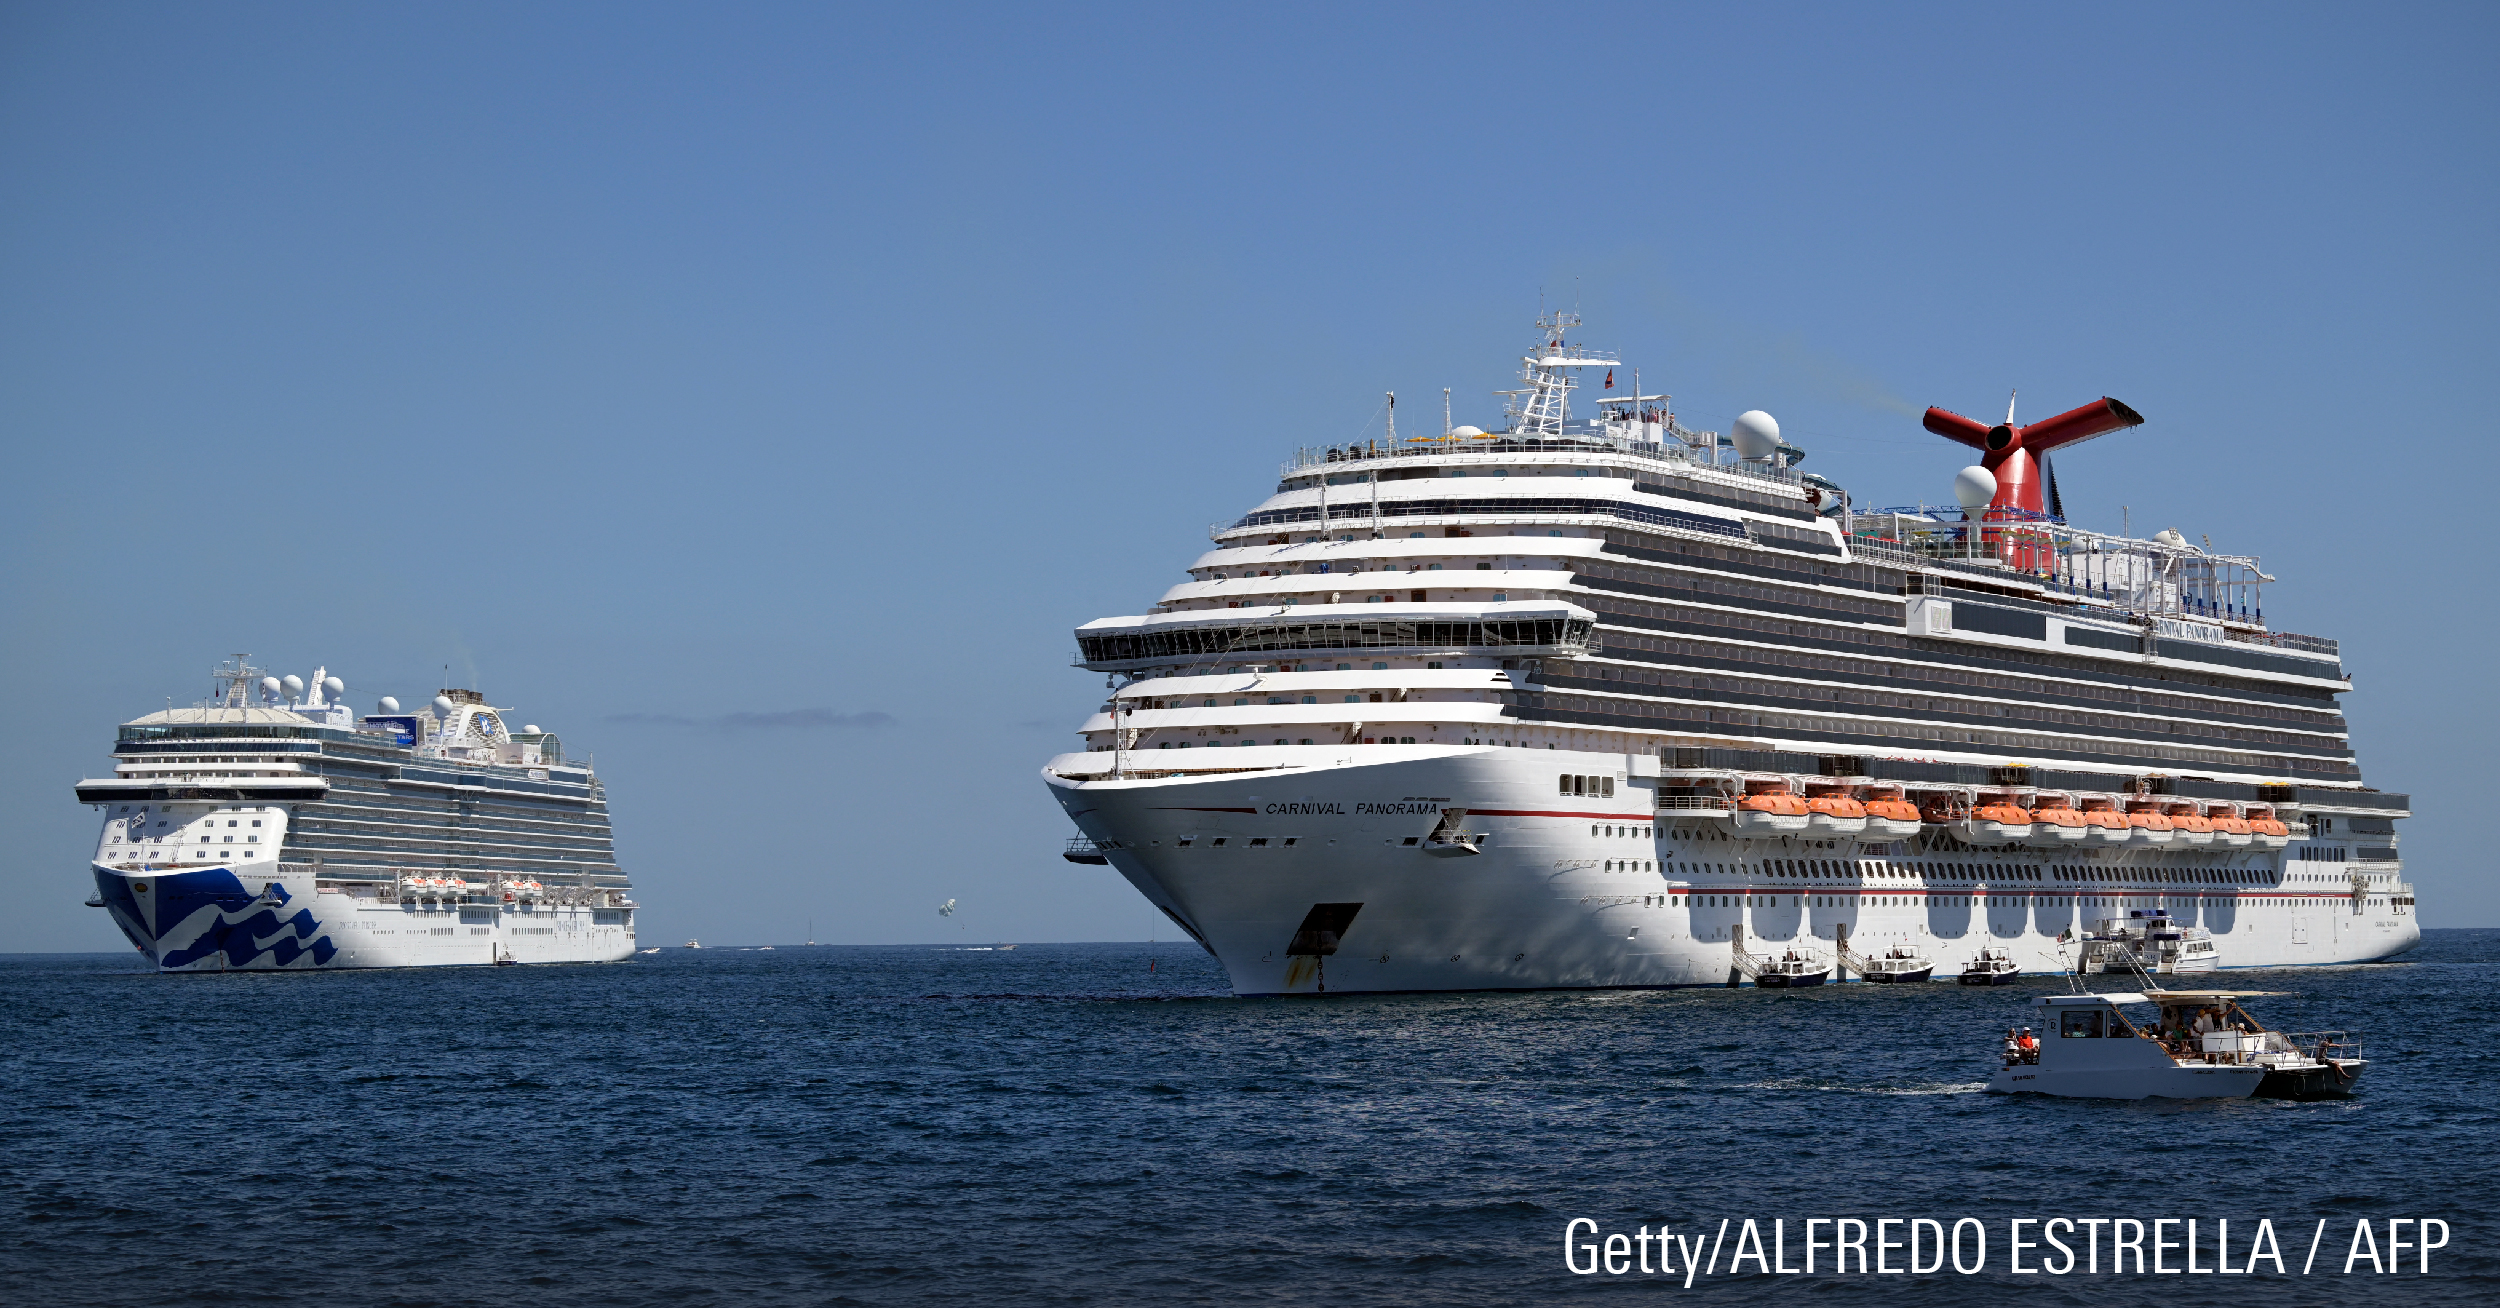
For cruise lines, advanced ticket sales have been “robust,” according to Morningstar analysts. Total deposits of the four publicly traded cruise operators were roughly $17 billion in the first quarter of 2024, an increase of 17% over last year. “This figure conveys a higher commitment to cruising than before the coronavirus pandemic, when the operators held $10 billion in advance ticket sales,” Katz and Wasiolek say.
2024 Travel Forecasts
These are Katz and Wasiolek’s predictions for the year:
- Hotels: Sales can increase by 7% on average as business and international travel lift hotel operator performance.
- Global distribution systems: Sales can grow by 9% on average, benefiting from a recovery in business travel.
- Online travel agencies: Sales growth averages 9%, helped by mobile and alternative accommodation options.
- Cruises: Sales should rise 14% on average, stemming from optimized capacity.
Here’s a closer look at Katz and Wasiolek’s top four travel stocks.
Carnival
- Fair Value Estimate: $28.00
- Morningstar Rating: 4 stars
- Morningstar Economic Moat Rating: Narrow
- Fair Value Uncertainty: High
“We believe Carnival shares are incorporating either a slowdown in leisure demand or pricing growth, rather than improvement stemming from increased penetration of the global travel demand base. Moreover, we think Carnival is uniquely positioned to benefit from a more efficient fleet composition (after disposing of 26 ships in 2020-22), which should benefit the cost structure more than initially expected, particularly with the fleet at full deployment.
“With the industry operating at full occupancy, opportunities to improve Carnival’s profit margins should surface. These include increased scale, improved brand awareness via tactical marketing spending, and better profitability from its mix. These factors should help increase adjusted EBITDA margins to around 27% at the end of our forecast, supported by low-single-digit price and cost growth. This is in line with the average EBITDA the company achieved in the five years ending in 2019.”
Read more of Jaime M. Katz’s commentary here.
Sabre
- Fair Value Estimate: $5.00
- Morningstar Rating: 4 stars
- Morningstar Economic Moat Rating: Narrow
- Fair Value Uncertainty: Very High
“We think concerns about Sabre’s financial health, competitive positioning, and lower corporate travel demand have presented an opportunity to own a company with a network, efficient scale, and switching cost advantages at an attractive margin of safety.
“Sabre’s global distribution system holds material aggregation and processing advantages over competing alternatives. Although we think some corporate travel could be displaced in the long term by video conferencing, we still expect business trips to rebound. As a result, we believe Sabre’s sales can return to 2019 levels by 2028.”
Read more of Dan Wasiolek’s commentary here.
Expedia Group
- Fair Value Estimate: $185.00
- Morningstar Rating: 4 stars
- Morningstar Economic Moat Rating: Narrow
- Fair Value Uncertainty: High
“We believe Expedia shares are discounting the benefit of enduring travel demand and investments the company has made the past few years. We surmise these will drive expanding operating margins and ongoing sales growth while supporting the company’s network effect.
“The company has restructured its platform from a less effective ‘invest in every brand in all regions’ approach to investing only in brands in specific regions where they are resonating with travellers. It has also allowed for the sharing of consumer data analytics and loyalty status across its portfolio, which should drive market efficiencies and high-quality traffic to its platform, buttressing its competitive position. As a result, we expect strong sales growth of 6% on average during the next 10 years, with operating margins of 12.7% in 2033 versus the 7.5% reported in 2019.”
Read more of Dan Wasiolek’s commentary here.
Norwegian Cruise Line Holdings
- Fair Value Estimate: $30.00
- Morningstar Rating: 4 stars
- Morningstar Economic Moat Rating: Narrow
- Fair Value Uncertainty: Very High
“Norwegian’s use of strategic marketing rather than excessive discounting to fill ships gives us confidence in its ability to lift pricing during periods of stable economic growth. In our opinion, this positions Norwegian to achieve 3%-4% average yield growth over time. Along with the shift in fleet mix, this should help the firm reach high-20% EBITDA margins over the next decade, near the 31% rate it booked before the pandemic in 2019.
“Moreover, the risk of value-destroying capital raises is insignificant, as the company refocused on shoring up its balance sheet. The company has around $1.7 billion in borrowings coming due over the next 12 months and had $2.4 billion in liquidity as of March 31. As such, we see the risk of an equity raise as negligible. Rather, we think shares remain depressed, given investor concern around a potential recession and its potential impact on discretionary spending.”
Read more of Jaime M. Katz’s commentary here.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States