
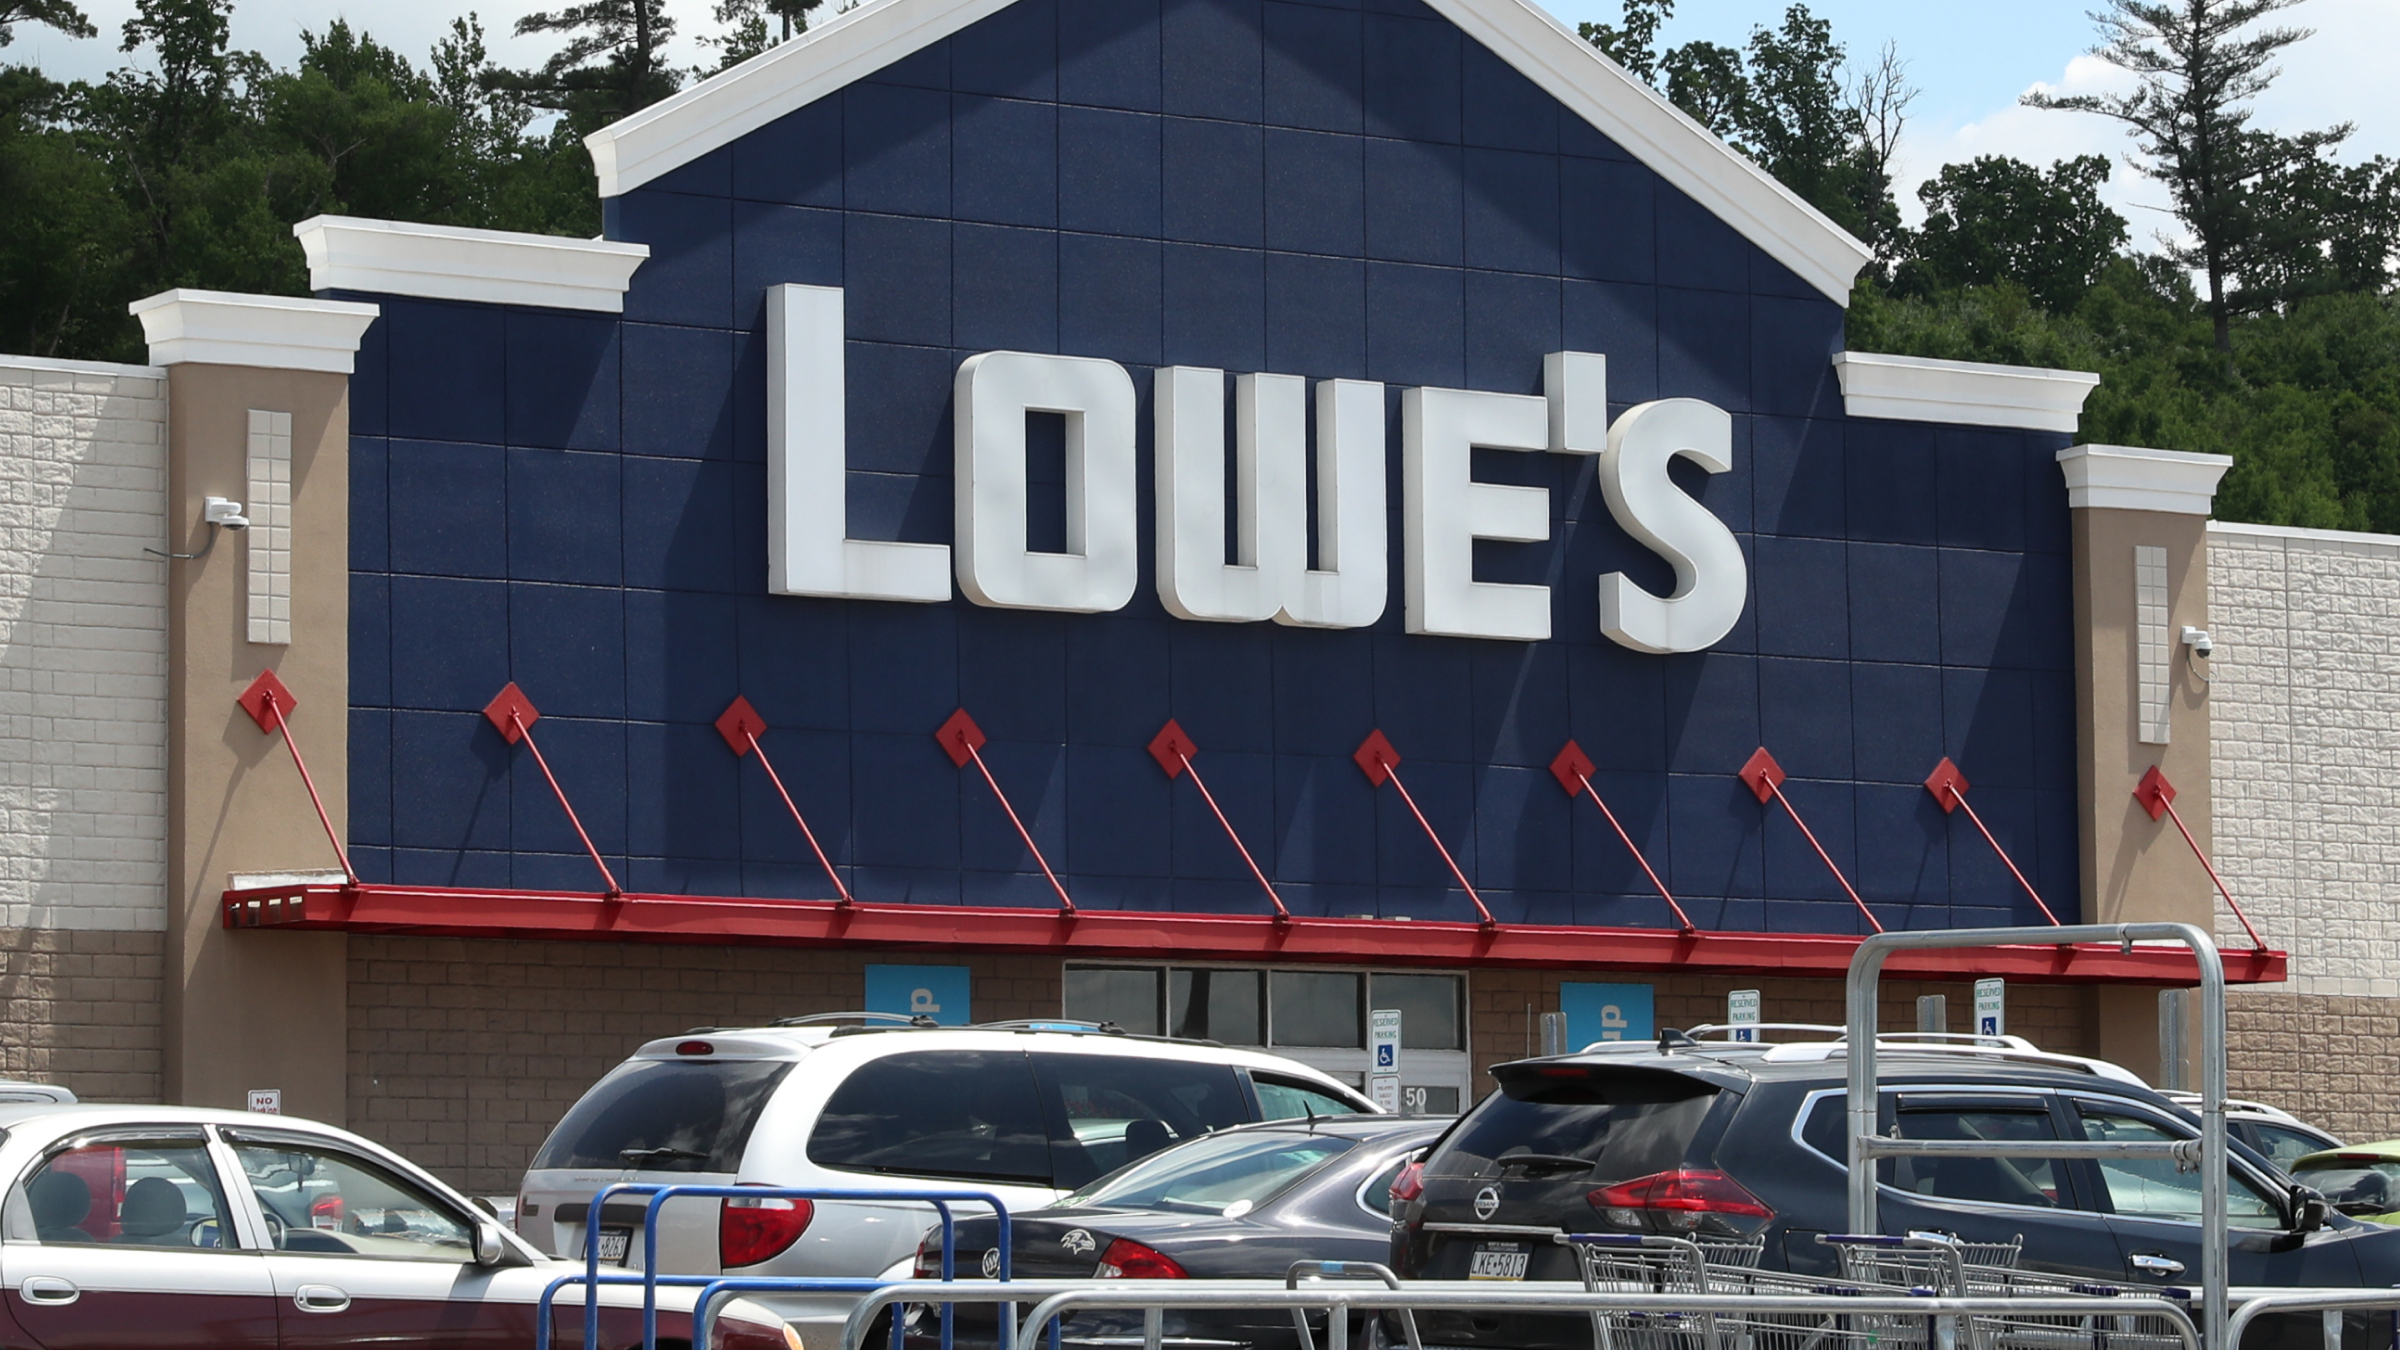
Lowe’s Earnings: Even in a Weak Housing Market, Sales Growth Remains Achievable
We plan to slightly lower our fair value estimate of Lowe’s stock.
Key Morningstar Metrics for Lowe’s
- Fair Value Estimate: $255.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
What We Thought of Lowe’s Earnings
Lowe’s LOW third-quarter sales rose 9.3%, bolstered by 1.8% comp store sales and pro sales stemming from acquisitions. While the firm raised its 2026 sales outlook to $92.5 billion (from $92.0 billion prior), it held its adjusted EPS target of $12.25, despite $250 million in recent tariff refunds.
Why it matters: Higher fuel and freight costs have been a headwind to Lowe’s ability to get operating expense leverage from sales growth. While the firm will be lapping higher input costs, it is unlikely to have a similar gain from refunds in 2027, bounding near-term profit upside.
- In addition, the consumer remains stretched by inflationary pressures, leaving discretionary home improvement project demand at risk. This has led to comparable transactions falling 1.7%, as store trips have become more needs-based (ticket rose 3.5% from mix and inflation).
- Still, we think Lowe’s continues investing in areas that support conversion, including efforts in loyalty, fulfillment (online), and the value proposition. Catering to evolving demand trends underlies our 3.5% long-term sales growth projection.
The bottom line: We plan to lower our $255 per share fair value estimate for wide-moat Lowe’s by around 5%. The change stems from a 40-basis-point downtick in our terminal operating margin outlook (to 13.3%) to account for distribution and interior solutions comprising a bigger mix of sales.
- Shares have been stymied by a weak housing market, which has hurt profitability, but we still view the long-term opportunity set favorably. Underlying this thesis is an aging housing stock and a housing supply shortage that should drive both existing home upgrades and new home builds.
Coming up: Lowe’s will update its strategic plan at its Dec. 9 investor day. We expect Lowe’s to focus on its sales growth strategy, particularly across the pro landscape, and how the customer service experience, value proposition, and productivity initiatives will drive improvement.
Editor’s Note: This analysis was originally published as a stock note by Morningstar Equity Research.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States