
Consumer Cyclicals: Investors Should Take Advantage of Select Opportunities to Splurge
Kohl’s and Hanes are among our top picks in this sector.


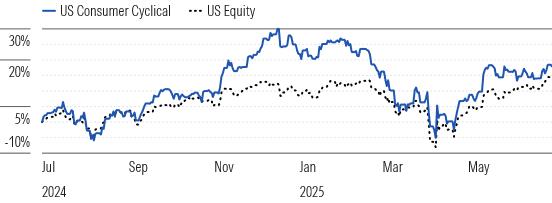
The Morningstar US Consumer Cyclical Index’s 19.55% rise in the second quarter was only modestly behind the market’s 22.8% uptick. Despite this, nearly half of our sector coverage resides in 4- or 5-star territory, with the median stock trading at a 14% discount to its fair value estimate.
Consumer Cyclical Shares Nearly Match the Market’s Mid-Single-Digit Q2 Ascent
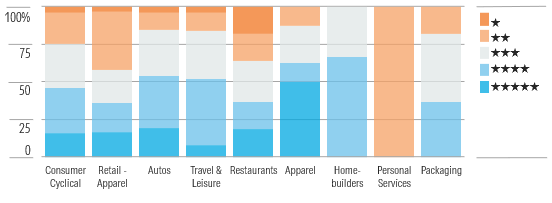
We see particular value in travel and leisure (which trades at a nearly 20% discount) and apparel (a 49% discount). We surmise concern is anchored in the financial burdens consumers face in this uncertain economic landscape and its potential impact on discretionary spending.
Bargain Hunters Can Find Value in the Travel and Leisure and Apparel Enclaves
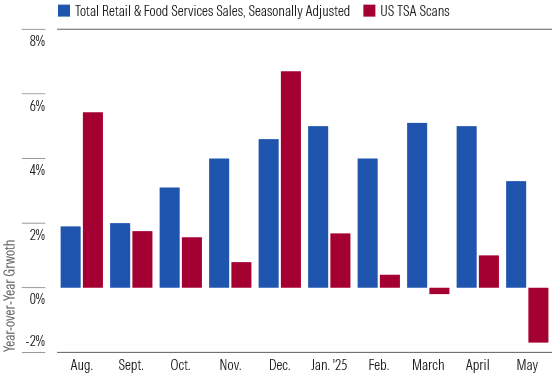
We have begun to see this manifest in declining US airline passenger counts, which have slowed from low-single-digit growth to a nearly 2.0% drop in May 2025 and a 1.5% decrease in June through the 24th. This trend not only affects airlines but also hotels, cruise lines, and online travel companies. However, we attribute this to a pullback in business travel, as corporations look to ratchet back their spending in these volatile economic times. From our perspective, consumers continue to show an interest in leisure trips and experiences. As such, we don’t expect the downturn to prove pervasive. Even as consumers have tightened their purse strings, we view the human-ingrained desire to travel as a tailwind for the industry in the long term.
TSA Scans Slip Despite Fairly Consistent Growth in Retail and Foodservice Sales
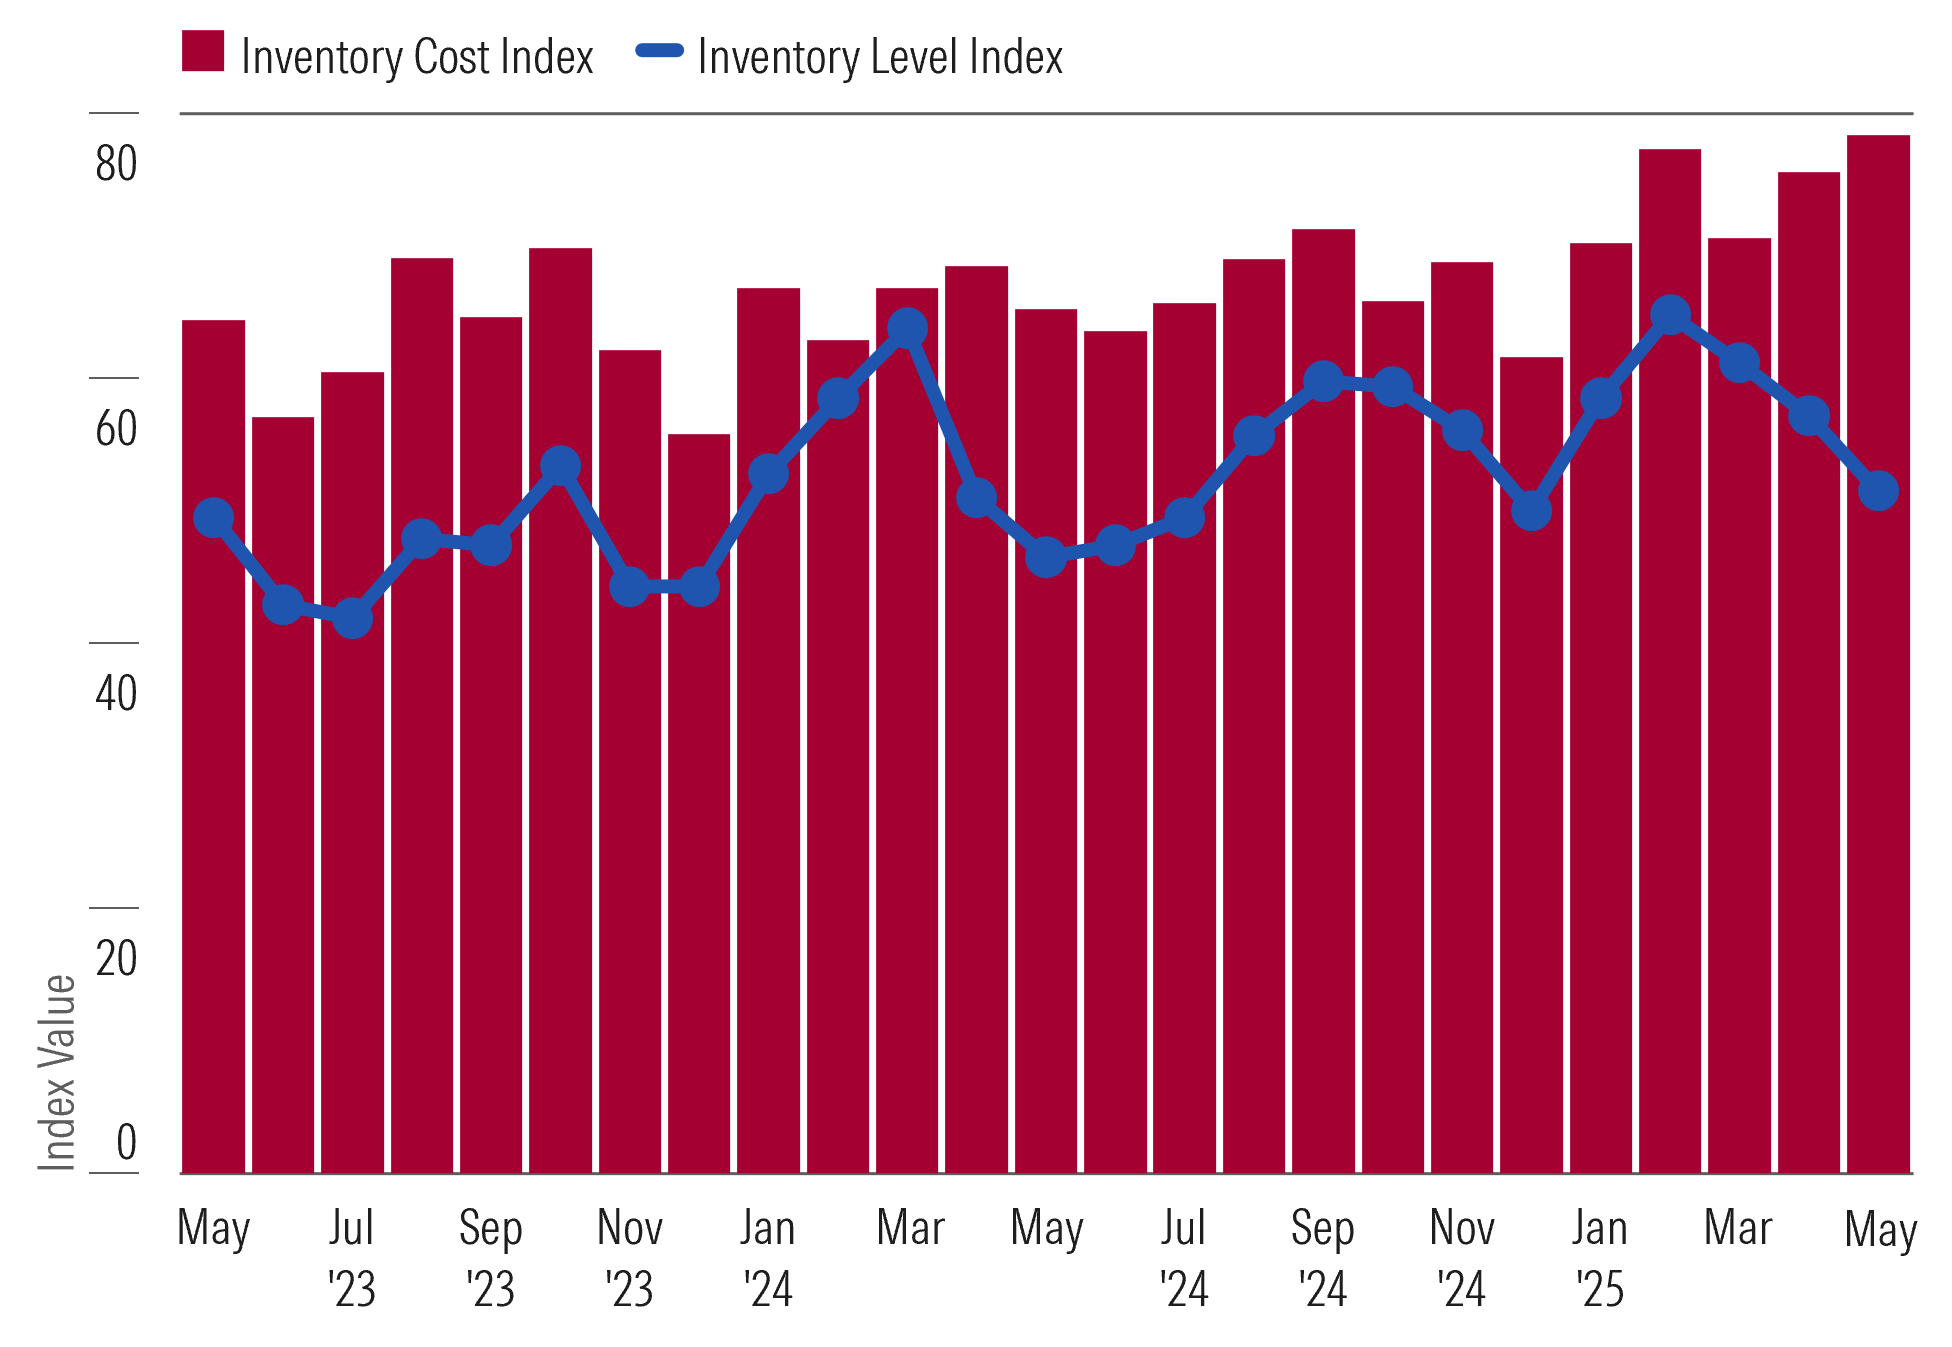
As the consumer spending backdrop remains fragile, though, we aren’t surprised the Logistics Managers’ inventory level index has contracted. If retailers hold significant inventory, this can lead to extreme discounting to clear excess stock promptly. The inventory cost index has been on an upward trajectory since the end of 2024. We attribute this to overall inflation, accentuated by tariffs. As such, we expect firms to employ a few tactics (pursuing cost savings and siphoning discretionary spending) before raising prices.
While Inventory Levels Have Been Edging Down, Costs Remain Elevated
Top Consumer Cyclical Sector Picks
Kohl’s
- Fair Value Estimate: $40.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: None
- Morningstar Uncertainty Rating: Very High
We believe no-moat Kohl’s KSS is an attractive investment opportunity, trading at around an 80% discount to our $40 fair value estimate. Although traditional department stores are struggling, Kohl’s has substantial e-commerce, as its large store base allows it to ship directly from stores and encourages buying online and picking up in stores. In addition, its partnership with Sephora has enhanced its beauty business and made it more competitive with other department stores and Ulta. We expect Kohl’s to maintain its focus on its loyalty program, Sephora, inventory management, and debt reduction.
Nike
- Fair Value Estimate: $112.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
Wide-moat Nike NKE is in 4-star territory, with shares sitting at a 37% discount to our $112 fair value estimate. We rate Nike, the global sportswear leader, as a wide-moat company based on its brand intangible assets. Its sales growth has stalled, but it achieves premium prices for its products through its innovation, marketing, and direct selling. Nike is also cutting costs through restructuring efforts, planning to reduce annual expenses by $2 billion by 2026. Areas of growth for Nike include China, and as the market leader, it should continue to benefit from government investment in athletics.
Hanesbrands
- Fair Value Estimate: $16.30
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Very High
We believe narrow-moat Hanes HBI, trading at a 71% discount to our $16.30 fair value estimate, presents an attractive investment opportunity. Hanes has leading brands in innerwear in North America and Australia but has struggled to generate sales growth. A year ago, Hanes announced the sale of Champion to Authentic Brands Group for an attractive price of $1.2 billion, plus the possibility of an additional $300 million in earn-outs. While this disposition will reduce future cash flow, we think it also reduces risk, as the proceeds will be used for debt reduction. Moreover, we think it will have a positive effect on profit margins.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States