
Communications Services: Growth at Alphabet and Meta May Slow, but They Should Maintain Ad Dominance
Alphabet and Comcast are among our favored stocks in the sector.

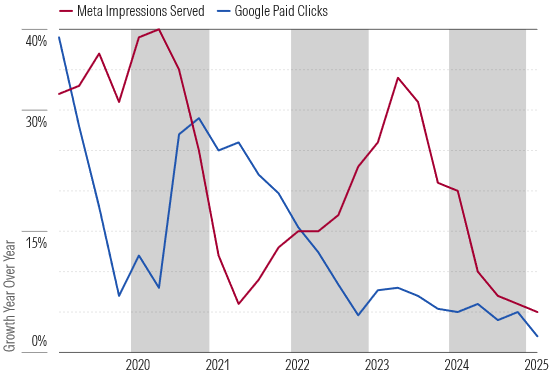
Meta Platforms META and Alphabet GOOG continue to post solid growth in advertising revenue, but some signs of weakness have emerged. Both firms reported the slowest ad volume growth on record recently during the first quarter—clicks on paid search links for Google and ad impressions for Meta. While the nature of search is changing with the rise of ChatGPT and other AI tools, Google remains by far the most widely used method for finding information. We suspect the slowdown in click growth primarily reflects the market’s maturity after a period of robust growth following the covid-19 pandemic.
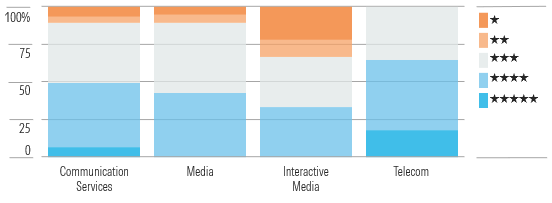
Outside of Alphabet, Most Large Communication Services Stocks Have Performed Well

Meta is similarly progressing toward maturity, with more than 4 billion people using its platforms monthly. The firm’s network effect remains extremely powerful, however. It has added more than 500 million monthly active users over the past three years, nearly equal to Pinterest’s entire user base. Only TikTok has rivaled Meta’s scale, but the Chinese firm’s fate in the US rests in the hands of lawmakers. We don’t expect an outright TikTok ban, but it remains a possibility that could significantly benefit Meta and Alphabet’s YouTube platform.
Canadian Telecom Shares Are the Cheapest Corner of the Sector
Red-hot demand has fueled ad growth recently. Ad prices have moved steadily higher, as spending has limited alternatives to the two ad giants. Over the longer term, we expect new AI tools will help rivals steal consumer attention and make ad creation, placement, and measurement across multiple platforms more efficient. Alphabet and Meta have their own deep AI resources to fight back, but we believe their dominance will decrease somewhat. In the next term, potential economic weakness and a corresponding pullback in ad demand are a bigger threat to growth.
Advertising Volume Growth Has Slowed Sharply For Meta and Alphabet
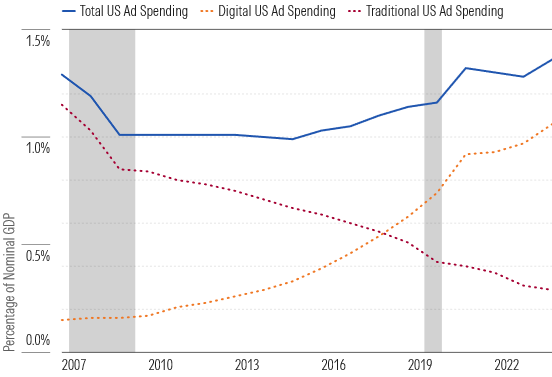
Advertising spending in the United States has grown faster than the economy over the past decade, but its share of nominal GDP only recently returned to levels seen prior to the financial crisis. Ad spending usually contracts sharply when the economy weakens, but that didn’t happen during the pandemic recession. Marketers quickly reallocated ad spending to digital formats to reach consumers as habits were quickly changing. Now that digital ads compose 80% of the total market, we expect demand will show more volatility in a recession.
Even With a Recent Growth Spurt, US Ad Spending Is Tied Closely to the Economy
Top Communication Services Sector Picks
Alphabet
- Fair Value Estimate: $237.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
We believe investors are overly pessimistic when it comes to antitrust concerns around Alphabet, as well as its competitive positioning in AI. On antitrust issues, we think the worst-case scenario (a breakup) is highly unlikely, and that the company will be able to navigate remedies without materially damaging its core business. We also see Alphabet as one of three credible leaders in public cloud, and think it is well-positioned to benefit from surging interest in generative AI. We believe Alphabet’s Gemini model, along with a variety of products that it powers, including a chatbot and productivity tools, can stand toe to toe with solutions from other industry leaders.
Warner Bros. Discovery
- Fair Value Estimate: $20.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: None
- Morningstar Uncertainty Rating: Very High
Though traditional television pressure is likely to worsen, the rest of Warner’s WBD business is looking up, and the company’s split, expected in 2026, should help unlock the value we’ve long seen. Streaming has turned profitable, additional HBO Max launches are coming, and the firm has seen success at the 2025 box office. The loss of the NBA will accelerate declines in television revenue, but the savings on rights costs should be well worth the tradeoff, boosting cash flow. The split should allow each business to pursue strategic moves and capital allocation policies best suited to their growth opportunities and cash flow potential.
Comcast
- Fair Value Estimate: $49.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Medium
We still favor Comcast CMCSA over other cable companies because of its stronger balance sheet, which provides flexibility to use cash flow to aggressively repurchase shares. We expect Comcast’s network will enable it to maintain the size of its broadband customer base over time while a rational competitive environment allows broadband prices to rise. Comcast will need to increase network spending in the coming years to keep pace with the phone companies’ fiber network capabilities, but we expect cable cash flow to still grow modestly over the coming years. The NBCUniversal business isn’t as strong, but it remains an important media asset.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States