
Communication Services: If US Wireless Growth Slows, Temptation to Increase Promotions May Rise
Alphabet, Comcast, and Paramount are our top picks in this sector.


In early March, AT&T T and Verizon Communications VZ warned that a slowdown in wireless customer activity had prompted both firms to increase their promotional efforts. We don’t believe this warrants long-term concern, but it does highlight the issue with setting customer growth targets at the start of each year.
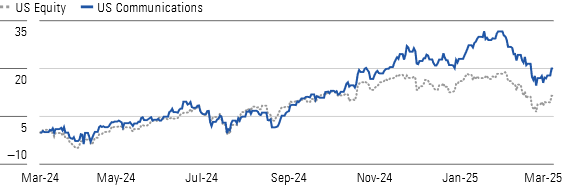
Telecom Gains Have Softened the Blow From Alphabet and Meta's Recent Decline
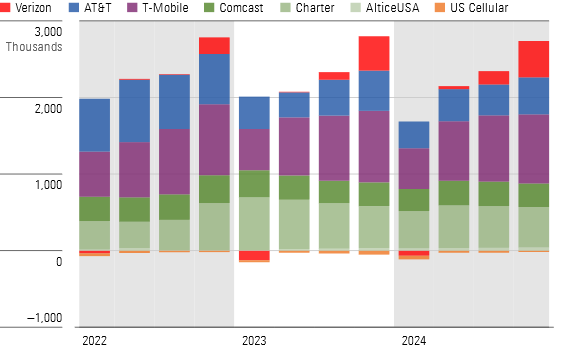
We still believe the competitive structure of the US wireless industry is favorable, as market share shifts very slowly and the three major carriers can easily retaliate against each other’s offers. However, if industry growth slows, they will be tempted to ratchet up promotions to hit their targets. The number of US postpaid wireless customers increased by more than 3% in 2024—the fourth consecutive year of strong growth—but growth will eventually have to slow to more closely match the total population. However, each of the carriers has reiterated its financial expectations for 2025, indicating that free cash flow across the group should remain strong despite competitive pressure.
We Still See Opportunities in Telecom
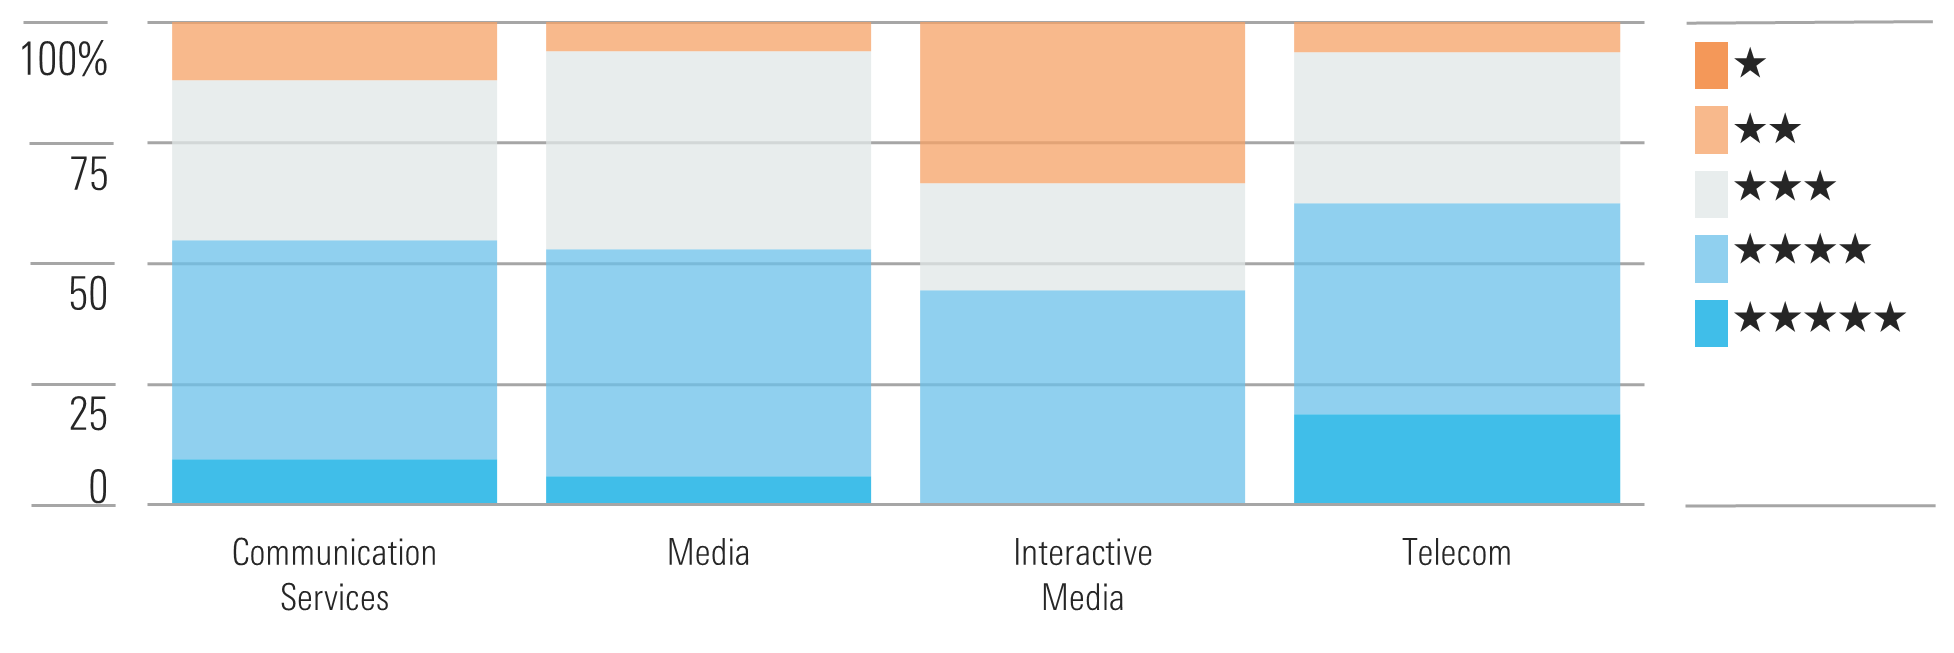
Advertising demand has shown no signs of slowing, at least through the end of 2024, with both Alphabet GOOG and Meta Platforms META posting accelerating ad revenue growth during the fourth quarter versus the third. Digital ad pricing remains very strong, offsetting decelerating user growth. For traditional media firms, political ad spending was a major boon; we estimate linear television ad revenue grew for the first time since 2021 during the second half of 2024. However, advertising demand is notoriously sensitive to economic swings, and political demand (which also benefits digital ad demand to some extent) won’t recur in 2025. While we believe both Alphabet and Meta are very well-positioned competitively, we wouldn’t be surprised if revenue growth slows in the coming quarters, given the current economic uncertainty.
Quarterly Net Postpaid Phone Customer Additions
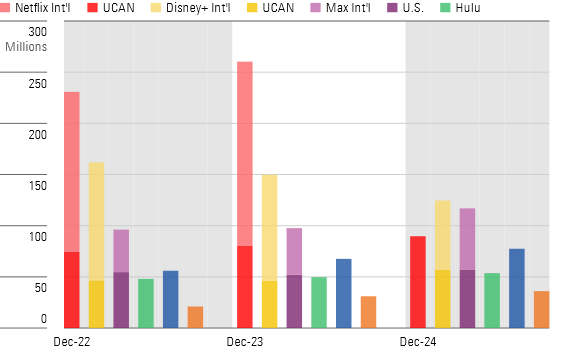
Although Netflix still has no peer among subscription streaming services, legacy TV firms have made big strides in expanding their customer bases and improving profitability. Both Max and Paramount+ delivered near-record subscriber additions during the fourth quarter of 2024, driven by international expansion, increased bundling with other services, and increased live sports programming. On the other hand, Comcast’s Peacock service continues to disappoint. We look for Comcast to use its cable network spinoff to reshape its media assets in 2025.
Global Video Streaming Subscribers
Top Communication Services Sector Picks
Alphabet
- Fair Value Estimate: $237.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
We believe investors are overly pessimistic about antitrust concerns around Alphabet and its competitive positioning in artificial intelligence. On antitrust issues, we think the worst-case scenario (a breakup of the firm) is highly unlikely, and that the company can navigate remedies without materially damaging its core business. We also see Alphabet as one of three credible leaders in public cloud, and that it is well-positioned to benefit from surging interest in generative AI. We believe Alphabet’s Gemini model, along with a variety of products that it powers, including a chatbot and productivity tools, can stand toe to toe with solutions from other industry leaders
Paramount
- Fair Value Estimate: $20.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: None
- Morningstar Uncertainty Rating: Very High
Paramount’s PARA valuation has been depressed, as its traditional television business has been crumbling and its fledgling streaming service has been bleeding cash. We see a few reasons the stock’s future looks brighter. We still expect the merger with Skydance to close. Shareholders can exchange at least half of their shares for $15 in cash. While the amount is below our fair value estimate, submitting shares would offer a nice return quickly. Fundamentally, Paramount+ has recently seen good subscriber uptake and engagement, and the platform is moving toward profitability. Along with the networks business making up less of the total mix, we see a path to improving financial performance.
Comcast
- Fair Value Estimate: $49.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Medium
We still favor Comcast CMCSA over other cable companies for its stronger balance sheet, which provides flexibility to use cash flow to aggressively repurchase shares. We expect Comcast’s network will enable it to maintain the size of its broadband customer base over time, while a rational competitive environment allows broadband prices to rise. The firm will need to increase network spending in the coming years to keep pace with the phone companies’ fiber network capabilities, but we expect cable cash flow to still grow modestly over the coming years. The NBCUniversal business isn’t as strong, but it remains an important media asset.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States