
Consumer Defensives: Economic Malaise Leaves Advantaged Firms in the Bargain Bin
Kellogg and Campbell’s are some of our top stocks in this sector.

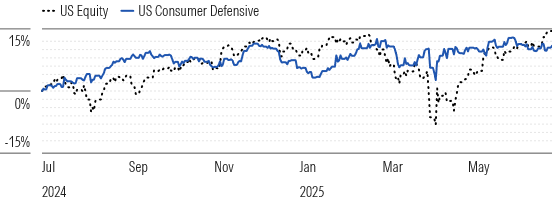
The Morningstar US Consumer Defensive Index ticked up 5% in the second quarter, lagging the market’s 22.8% rally. Around 40% of our coverage boasts a 4- or 5-star rating, with the median stock trading at a 7% discount to its fair value estimate.
Consumer Defensive Firms Trail the Market’s Mid-Single-Digit Rise in Q2
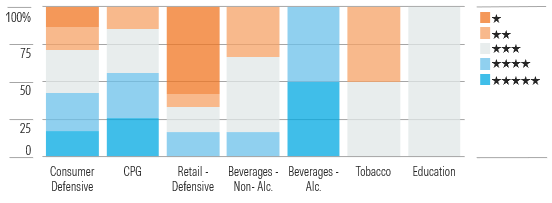
We identify undervalued ideas emanating from the alcoholic beverage sector, which is currently trading at an average 35% discount to our fair value estimates, as well as the consumer packaged goods sector (12%). We attribute the market’s concern to the unsettled global macroeconomic and geopolitical landscape, including unease surrounding tariffs and their ultimate impact on consumer spending. Despite lingering uncertainty, we think firms with solid brands and stalwart standings with retailers are poised to weather the current backdrop relatively unscathed.
Investors Should Feast on Alcoholic Beverage and CPG Opportunities
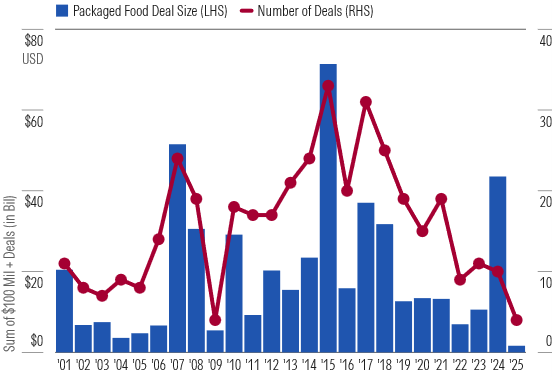
While growth has waned across the consumer products landscape as prices stagnate and volumes languish, companies haven’t resorted to acquisitions to buoy their prospects. There have been just four deals in 2025 so far (equating to $1.6 billion), down from an average of 13 ($17.5 billion) over the past five years.
We’ve long believed that tie-ups can enable consumer product firms to gain exposure to a new region by leveraging local market expertise regarding native consumers and the distribution network, reducing the inherent risk of expansion. Further, by acquiring niche start-ups, firms can test the waters of nascent categories and grease the wheels of their innovation cycles while opening previously locked retail doors for smaller operators. However, we are encouraged that firms aren’t just chasing growth at any cost, and we believe that investing in their existing mix is prudent for the long term.
Despite Souring Growth, Packaged Food Firms Lose Taste for Acquisitions
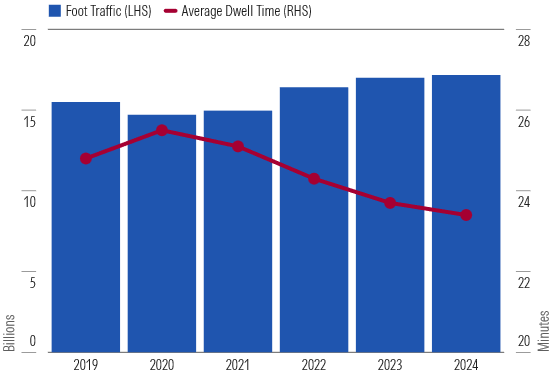
The challenge to ignite growth is exacerbated as consumers spend less time in stores (down to less than 24 minutes from about 26 five years ago), even as foot traffic has eclipsed pre-pandemic levels. If consumers don’t find the products they are looking for or the shopping experience is unfavorable, the odds are higher that they will abandon their basket and opt for another outlet. As such, retailers and manufacturers must work together to ensure the assortment resonates with consumers each time they visit a store.
With Shoppers Spending Less Time in Store, Onus Is on CPG, Retailers to Convert
Top Consumer Defensive Sector Picks
Kraft Heinz
- Fair Value Estimate: $51.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Medium
At around a 50% discount to our $51 fair value estimate and with a dividend yield of more than 5%, we believe narrow-moat Kraft Heinz KHC is attractive. We suspect investors are skeptical of whether the firm will avoid a material and lasting volume contraction in a tough economy amid intense competition after price hikes a few years back. However, we favor the firm’s efforts to unearth cost savings to fuel brand spending (research, development, and marketing), and believe this should help drive low-single-digit top-line growth in the long term against low-20s operating margins.
Campbell’s
- Fair Value Estimate: $62.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
Wide-moat Campbell’s CPB is appealing, trading at a nearly 50% discount to our $62 intrinsic valuation. In the face of concerns stemming from lagging volume trends, we posit that Campbell’s is making judicious investments to keep pace with evolving consumer trends. Furthermore, the firm is adjusting price points and pack sizes to ensure its mix appeals to value-focused consumers. We don’t think it will back down from these efforts; we forecast Campbell’s will continue to direct about 5% of sales to research, development, and marketing annually, leading to low-single-digit sales growth and high-teens operating margins in the longer term.
WK Kellogg
- Fair Value Estimate: $28.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: None
- Morningstar Uncertainty Rating: Medium
No-moat Kellogg KLG trades at a 45% discount to our $28 fair value estimate. While its singular exposure to the challenged cereal category and small scale have diminished its standing with retailers and suppliers, we see a path to higher profits. The firm’s priority remains upgrading an outdated supply chain, which we believe will enhance operational efficiencies and structurally lift margins, with our midcycle EBITDA margin exceeding 14% (from a trough of 9% in fiscal 2023). In our view, this should unlock the funds to invest in product innovation and marketing support, solidifying its standing in the mature domestic cereal aisle.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States