
Consumer Defensives: Competitively Advantaged Firms Are Well-Suited to Navigate Macroeconomic Waters
Campbell’s and Brown-Forman are among our top picks in this sector.

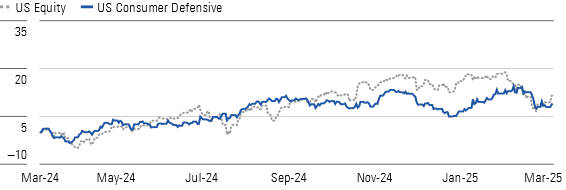
The Morningstar US Consumer Defensive Index rose 1.21% in the first quarter of 2025, outpacing the broader market’s 1.74% slide. While just under 40% of the consumer defensive landscape strikes us as undervalued, the median stock trades at a 4% discount to its intrinsic valuation.
Consumer Defensive Shares Boast Gains in Q1, Outpacing the Market's Decline
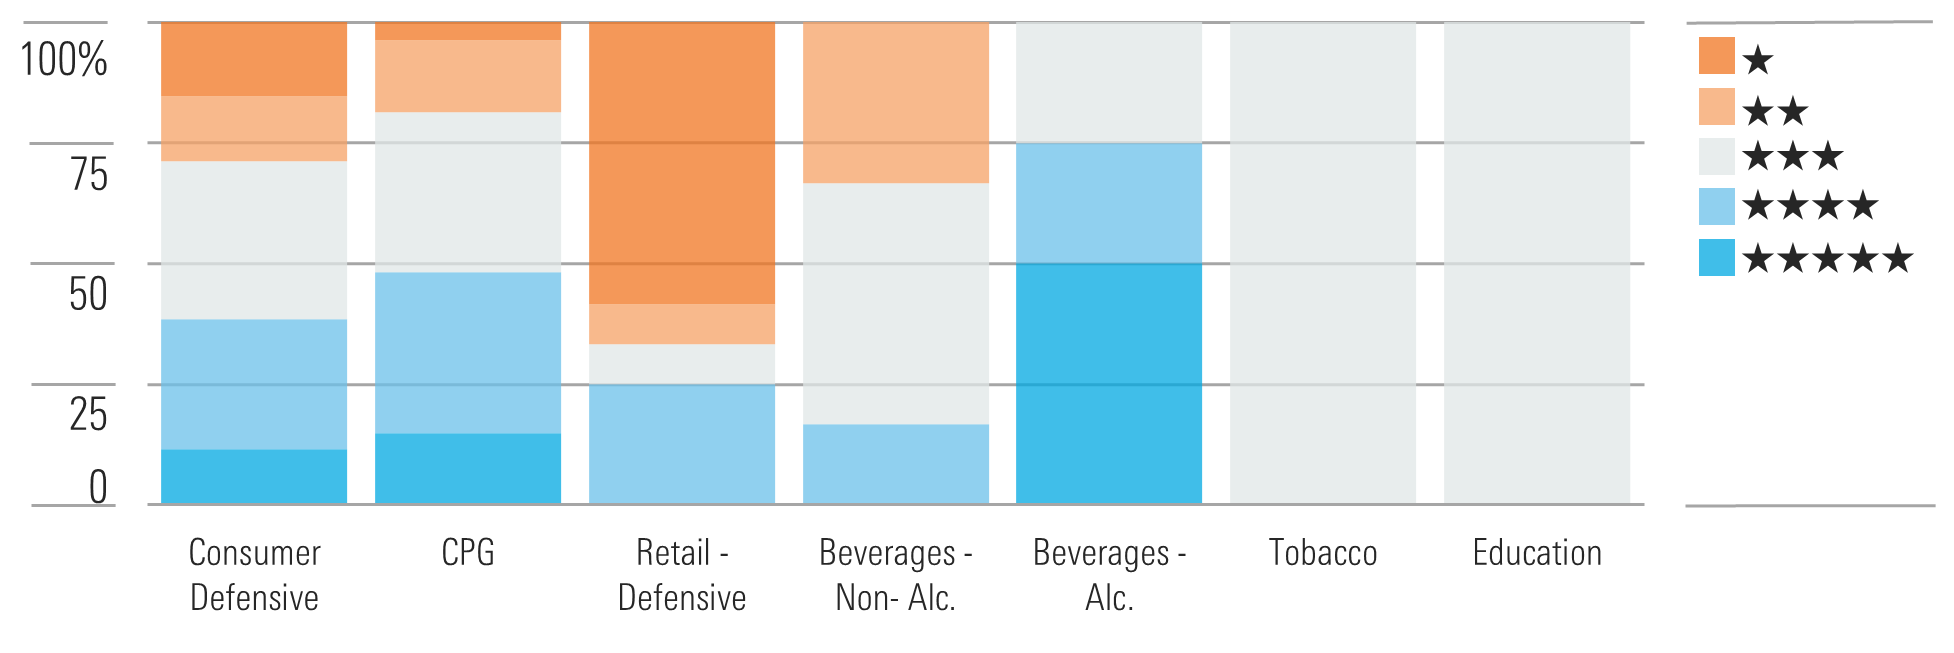
We see value in the consumer-packaged goods (13% discount) and alcoholic beverages (34% discount) subsectors, where an unsettled macroeconomic landscape (including the unease around tariffs) is straining consumers’ propensity to spend. This has been particularly pronounced among lower-income cohorts, resulting in stepped-up competitive intensity. Despite this pressure, we think moaty operators with solid brands and stalwart standings with retailers are poised to weather the malaise.
Bargains in the CPG and Alcoholic Beverage Aisles
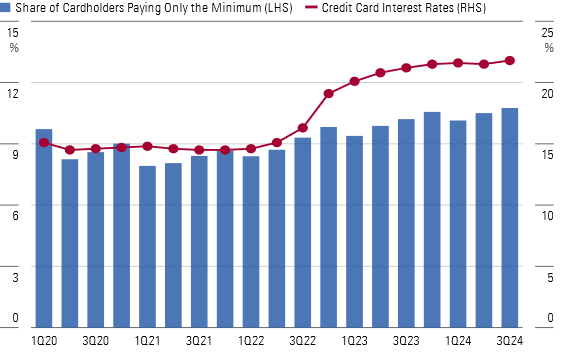
As personal savings have declined, we believe consumers are increasingly turning to credit cards to bridge the gap. However, many are struggling to manage mounting debt loads. In the third quarter of 2024, nearly 11% of consumers were making only the minimum monthly payments on their credit cards, up from around 8% in 2022. In this environment, we expect consumers to alter their spending habits, with increasing favor for lower-priced private-label products, particularly in categories where innovation fails to keep pace with evolving consumer trends. Against this backdrop, we believe moaty players maintain a stout arsenal to withstand short-term volume pressure and market share declines. Further, in our view, investments to strengthen their standing with retailers and consumers over the long term will remain a top priority.
An Increased Number of Credit Card Holders Paying the Bare Minimum
Despite these financial pressures, the value ascribed to convenience remains high. As evidence, online grocery sales across food, health and beauty, home, and nonalcoholic beverage products are growing. We believe that established manufacturers with brand equity and negotiating clout with retailers should benefit the most, as consumers often reorder or seek out familiar fare when shopping online. As such, brands and retailers must invest in appealing packaging while working to ensure product availability across all channels.
Consumers' Penchant for Purchasing Daily Essentials Online Continues to Grow
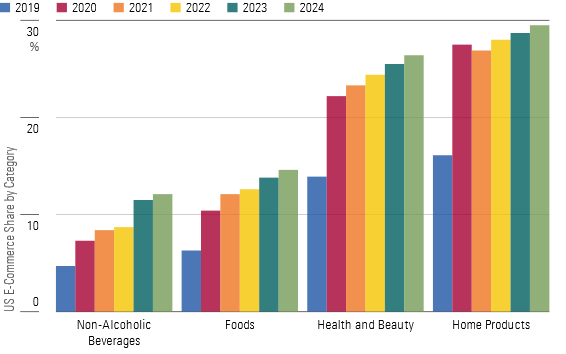
Top Consumer Defensive Sector Picks
Kraft Heinz
- Fair Value Estimate: $56.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: Medium
At around a 45% discount to our $56 fair value estimate and with a 4%-5% dividend yield, we think narrow-moat Kraft Heinz KHC is attractive. We suspect investors are skeptical of whether it will shun a material volume contraction in a tough economy amid intense competition after recent price hikes. However, we favor the firm’s efforts to unearth cost savings to support brand spending (research, development, and marketing), which should help drive top-line growth in the longer term.
Campbell’s
- Fair Value Estimate: $61.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
Wide-moat Campbell’s CPB is appealing, trading at a more than 35% discount to our $61 intrinsic valuation. In the face of concerns over lagging volume trends, we think the firm is judiciously investing to keep pace with evolving consumer trends. Further, the company is surgically altering price points and adjusting pack sizes to ensure its mix appeals to a value-focused consumer. We don’t think it will back down from these efforts. We forecast Campbell’s will continue to direct about 5% of sales to research, development, and marketing annually, leading to low-single-digit sales growth and high-teens operating margins in the longer term.
Brown-Forman
- Fair Value Estimate: $52.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
Trading more than 30% below our $52 per share fair value estimate, we believe shares of wide-moat Brown-Forman BF.B are striking. We acknowledge that uncertainty around tariffs has pressured the stock lately. Despite this, we expect the distiller will continue to thrive thanks to its advantaged competitive position and the Brown family’s long-term focus. Premiumization trends in spirits consumption and Brown-Forman’s strong innovation pipeline bode well for mid-single-digit top-line growth in the coming years.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States