
Technology: Strength Continues, Leaving the Sector Fairly Valued
Microsoft and STMicroelectronics lead our picks for this sector.

The technology sector’s good performance continued in the fourth quarter, and we see it as fairly valued overall. Persistently solid results for software companies finally led to a strong rally for the group from early September through early December, leaving the group slightly overvalued, in our view. Overall, tech was one of the strongest sectors in the fourth quarter, and it was the second-best-performing sector over the last 12 months. We see no consistent performance differentiation among market capitalization tranches. We remain confident in secular tailwinds in technology, such as cloud computing, artificial intelligence, and the long-term expansion of semiconductor demand. However, after its strong finish to 2024, we see limited near-term opportunities for the sector.
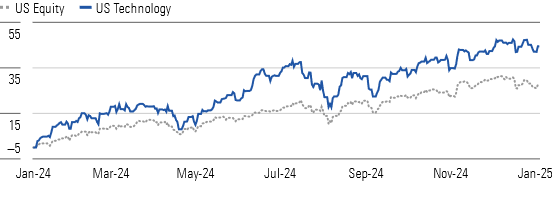
The Morningstar US Technology Index is up 36% on a trailing 12-month basis, compared with the US equity market being up 24%. Over the past quarter, the US equity market was up 3%, while tech was up 6%.
Technology Finished 2024 with a Bang
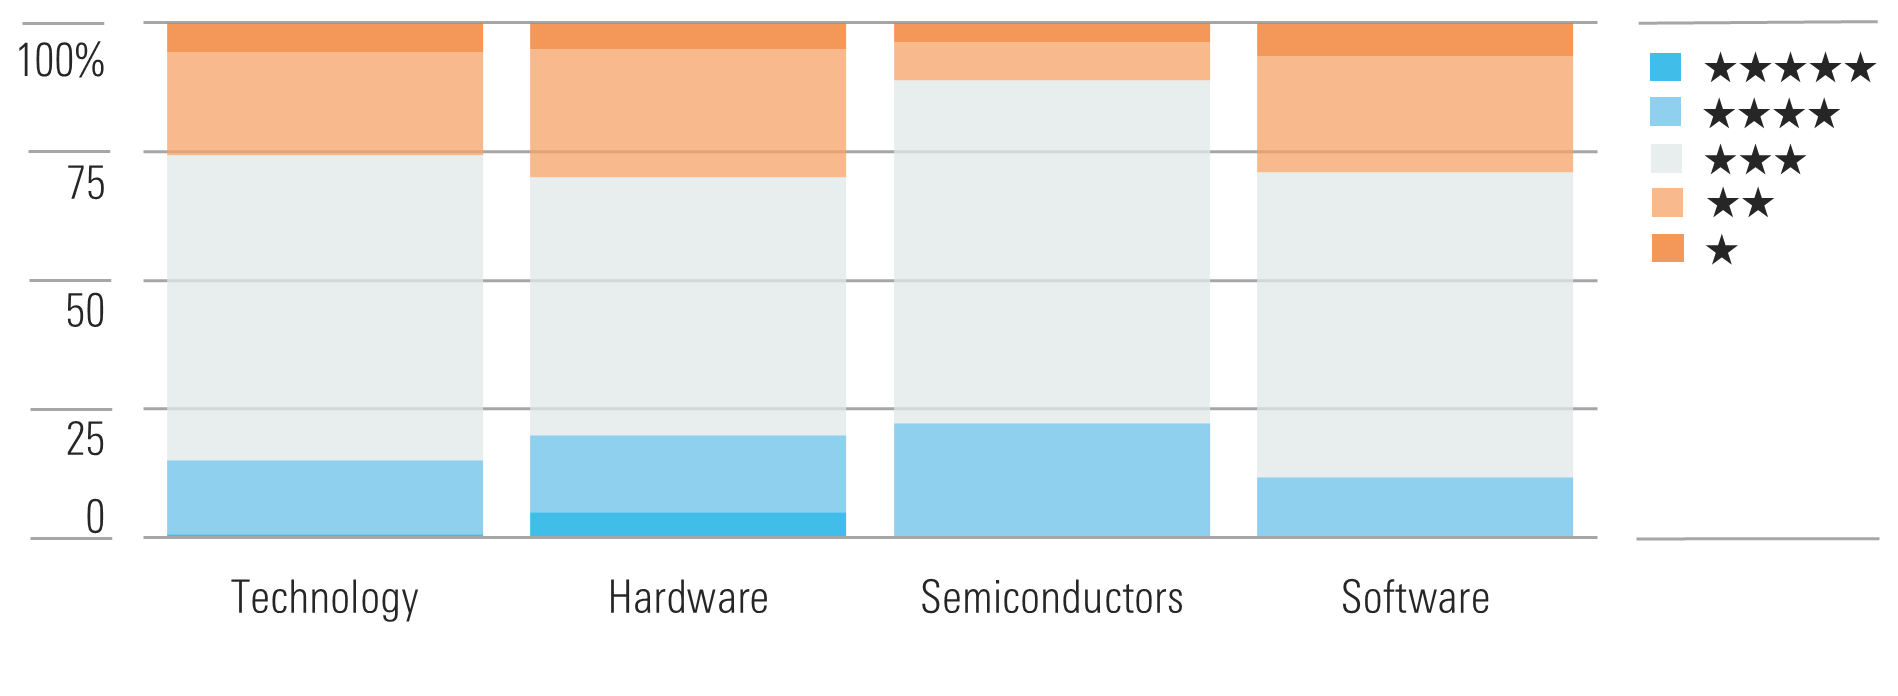
The median US technology stock is fairly valued, with a modest margin of safety. We see software and hardware as the most overvalued, with semis skewing the most attractive, as shown in the bottom panel at the right.
We See Limited Buying Opportunities in Technology
Generative AI remains the biggest theme within the sector. Software companies are developing and incorporating next-generation AI capabilities within their solutions, while cloud providers are introducing new services and ramping up capacity. Some semiconductor firms, notably Nvidia NVDA, are experiencing surging demand for AI and data center chip applications. That said, Nvidia shares surged earlier in 2024, but have leveled off lately despite continued demand strength.
Artificial Intelligence Should Drive Significant Growth in Semis
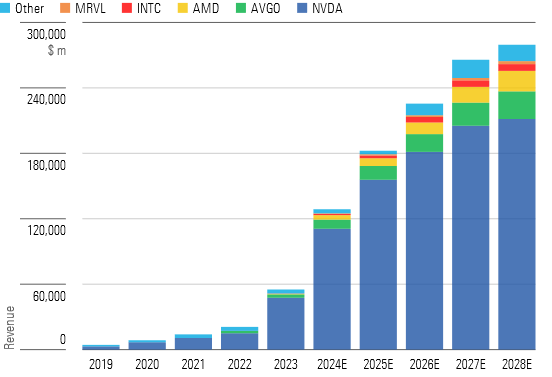
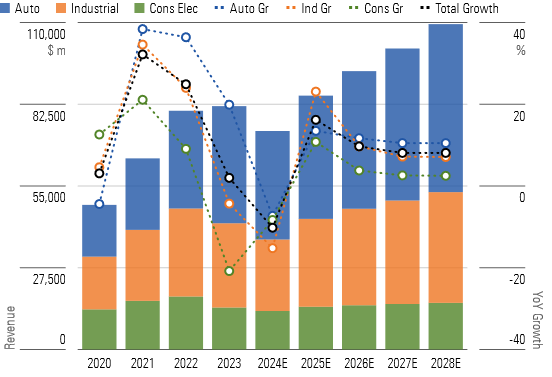
We expect AI accelerator revenue will increase by roughly 4 times over the next several years, making AI the largest growth driver in the semiconductor industry. We expect this to be led by Nvidia, but other firms should also benefit. Meanwhile, analog chip demand suffered in 2023 and 2024, with auto and industrial seeing softness, along with most other end markets. We believe in long-term structural growth tailwinds for analog, notably increasing semis content per vehicle, industrial automation, 5G rollouts, and other themes.
Analog Chips to Emerge From Cyclical Trough in 2025
Top Technology Sector Picks
NXP Semiconductors
- Fair Value Estimate: $300.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
NXP NXPI is one of our top picks in the analog and mixed-signal chip space. We’re especially fond of the company’s outsize exposure to the automotive end market, where it obtains nearly 50% of revenue. NXP is well diversified in automotive, with a nice product portfolio of processors, microcontrollers, and analog parts. We think the firm will also gain its fair share in electrification and safety automotive products, such as radar and battery management systems. Overall, NXP’s auto business is tied well to the secular tailwinds around rising chip content per vehicle, and we think the market is too focused on a near-term slowdown in demand. We expect NXP will return to revenue growth in 2025.
STMicroelectronics
- Fair Value Estimate: $44.00
- Morningstar Rating: ★★★★★
- Morningstar Economic Moat Rating: Narrow
- Morningstar Uncertainty Rating: High
STMicroelectronics STM is one of our top picks in the sector, as we think our fair value estimate offers an attractive margin of safety for long-term, patient investors. We continue to like the long-term secular tailwinds in the automotive end market, since STMicroelectronics should profit from increased chip content per car, especially in electric vehicles. The company has also achieved nice gross margin expansion in recent years, and we foresee it maintaining these margins in the long run.
Microsoft
- Fair Value Estimate: $490.00
- Morningstar Rating: ★★★★
- Morningstar Economic Moat Rating: Wide
- Morningstar Uncertainty Rating: Medium
Microsoft MSFT dominates several of its served markets, such as with Office in productivity software and Windows for PC operating systems. The firm has also established itself as one of two clear leaders in public cloud. We think the proliferation of hybrid cloud environments will continue to strengthen Microsoft’s position with Azure. Further, the company’s investment in OpenAI has catapulted Microsoft into a leadership position in generative AI, which has driven Azure’s growth in recent quarters. Our growth assumptions are centered around Azure, Microsoft 365 E5 migration, traction with the Power Platform for long-term value creation, and the proliferation of AI.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States