
Vanguard Wellington Is a Distinguished Balanced Fund
Disciplined management of the stock/bond split and rigorous bottom-up security selection have benefited long-term shareholders.
Key Morningstar Metrics for Vanguard Wellington
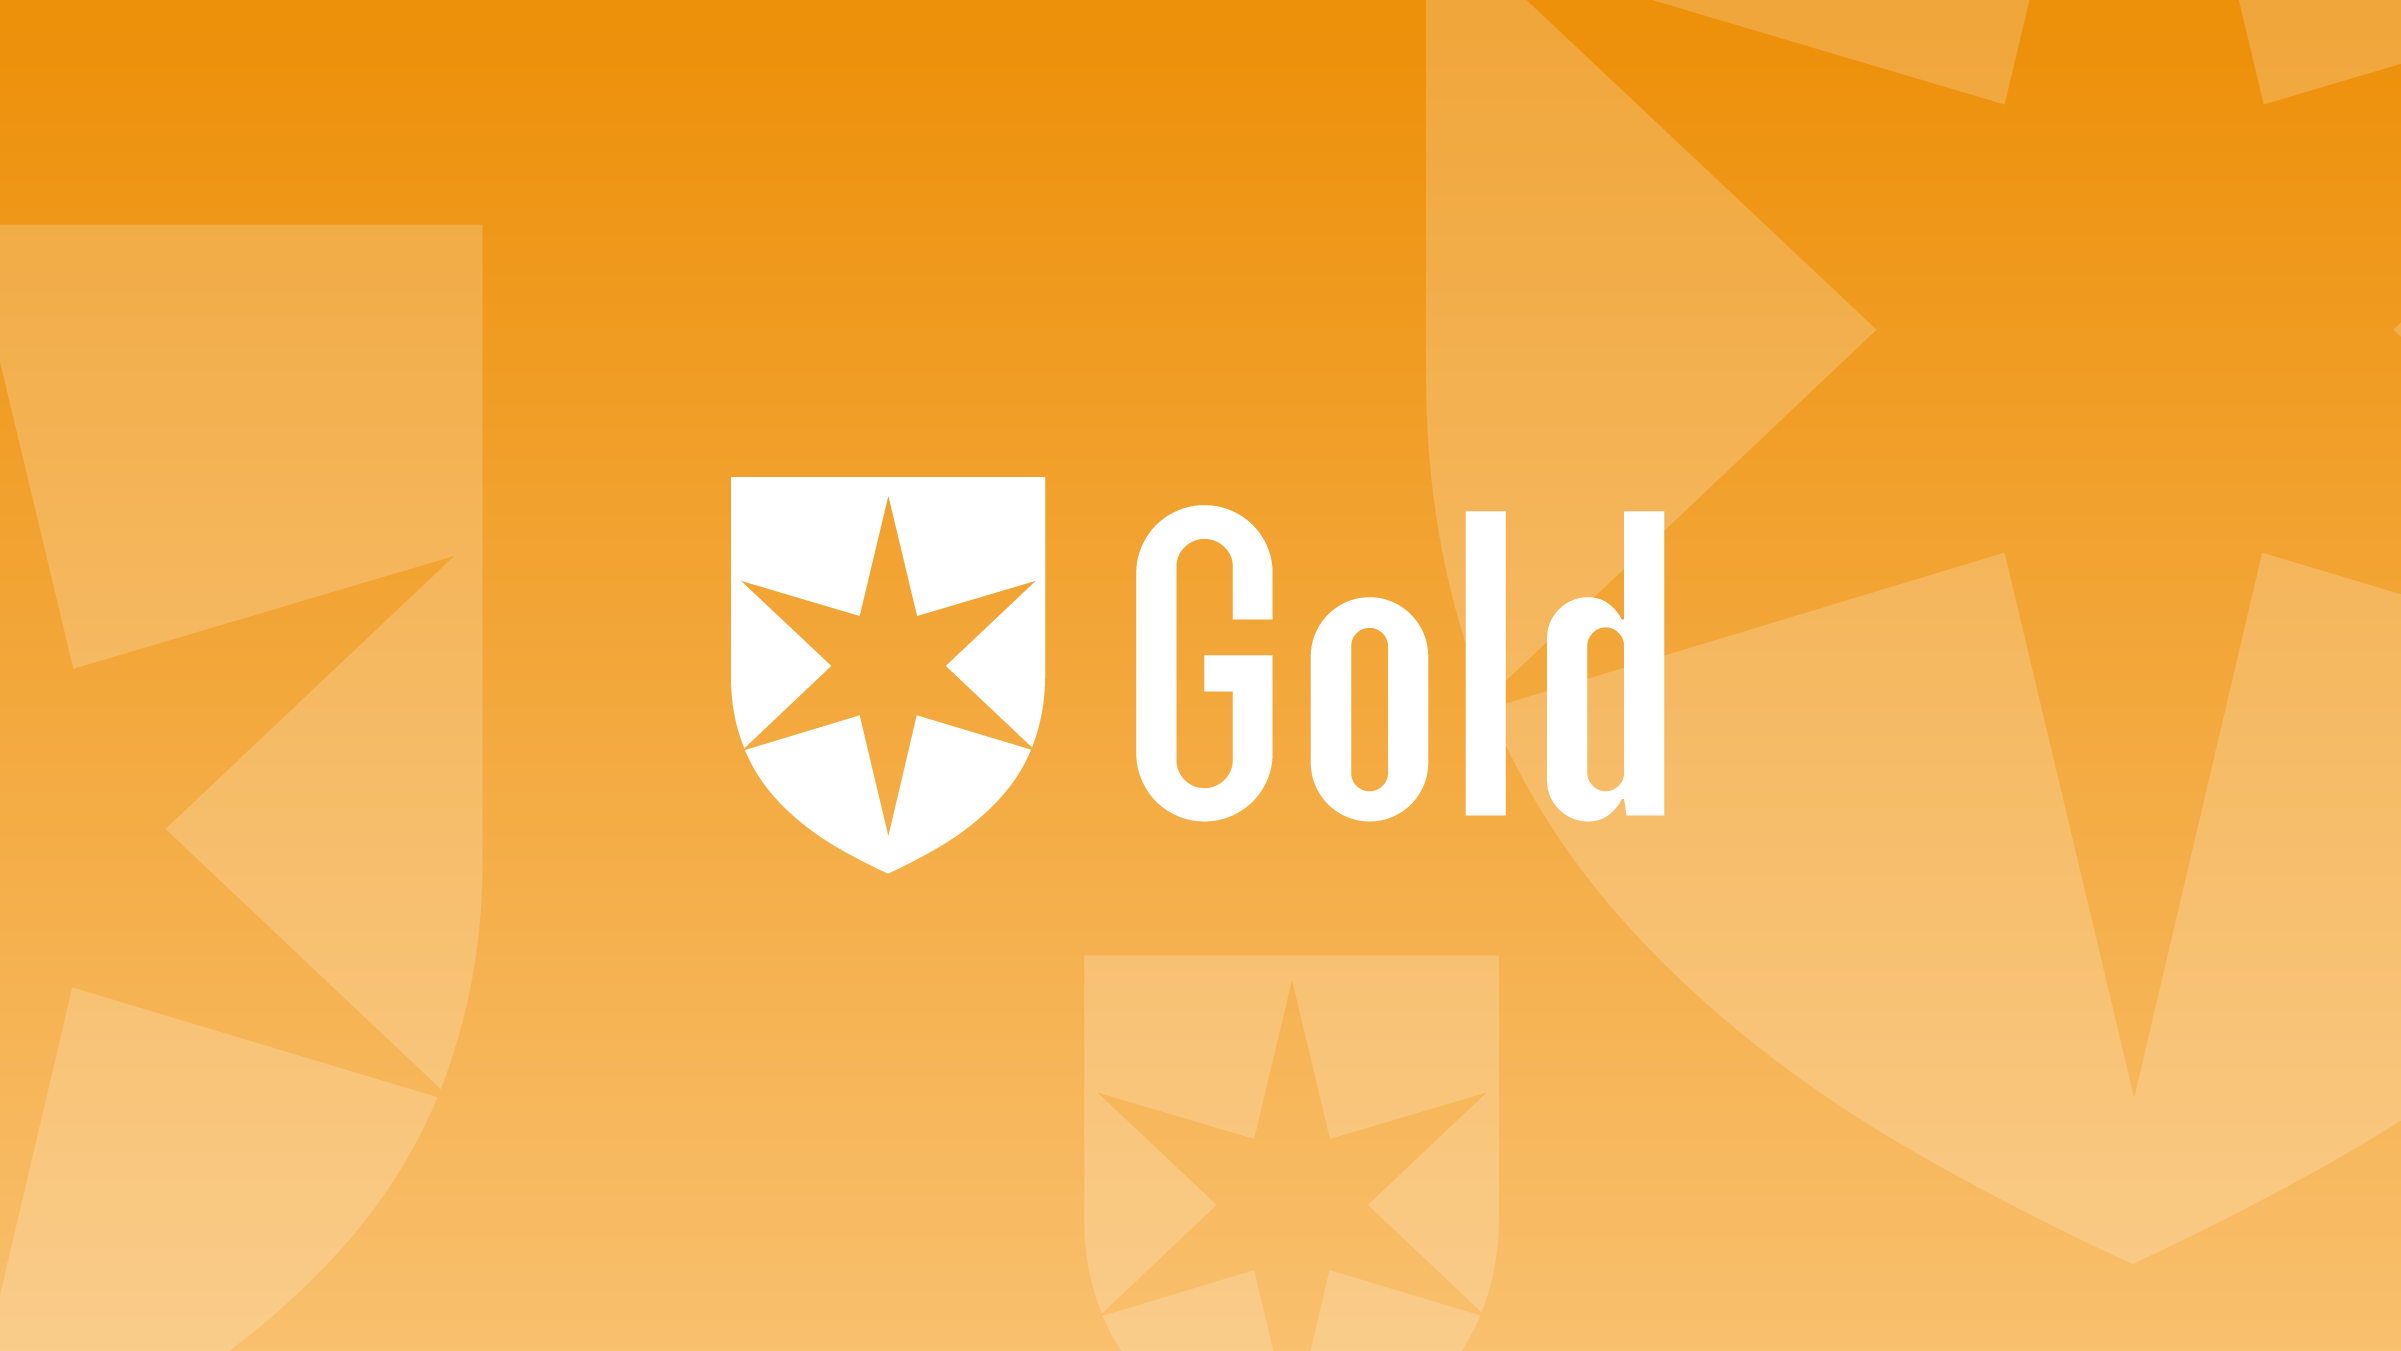
- Morningstar Medalist Rating: Gold
- Process Pillar: High
- People Pillar: Above Average
- Parent Pillar: High
Vanguard Wellington’s VWENX outstanding process is guided by experienced managers with significant resources at their disposal. Along with its attractive fees, this fund is a strong choice for investors seeking a steady allocation to stocks and bonds.
The fund continues to stand out under the stewardship of lead managers Daniel Pozen and Loren Moran. They lead the equity and fixed-income sleeves, respectively, and oversee the portfolio’s 65% equity/35% fixed-income allocation. Pozen is a 19-year Wellington veteran and started working on this fund in 2015. He took sole control of the equity sleeve when longtime manager Edward Bousa retired in 2020. Moran has comanaged the fund since 2017 and took the reins of the bond sleeve in 2021 after a multiyear transition saw two longtime managers retire in 2019 and 2021.
The stock/bond split can shift up or down by 5 percentage points, but Moran and Pozen keep the allocation very close to its strategic targets. Predicting short-term equity or bond outperformance is challenging. By maintaining a disciplined allocation, the team’s security selection, rather than asset allocation, will drive returns, which should continue to be a boon for long-term investors.
Pozen and his two dedicated analysts apply a rigorous intrinsic value approach to stock selection, pursuing quality companies that can create value through numerous market cycles. In 2024, the team introduced a new guideline: No single stock in the S&P 500 benchmark can contribute more than 10% of the portfolio’s active risk. This change was implemented to better manage significant active risk from large benchmark stocks, especially during periods of heightened index concentration. As a result, the managers may now include stocks they have less conviction in, as is the case with Tesla TSLA, which they added in mid-2024 at an underweight position (roughly 1.2% of the equity sleeve’s assets as of December 2024).
The fixed-income sleeve consists almost entirely of investment-grade bonds and is meant to complement the equity sleeve by acting as a ballast during times of equity volatility. Corporate credit has historically occupied around 60% of the sleeve, while around 20% is dedicated to asset-backed securities and taxable municipal bonds. US Treasuries and agency securities make up the final 20% and play an important role in liquidity management.
Vanguard Wellington: Performance Highlights
This fund has formidable long-term results. Over the trailing 15- and 20-year periods through February 2025, the Admiral share class outpaced both the moderate allocation Morningstar Category and the Morningstar Moderate Target Risk Index. Its risk-adjusted returns (as measured by Sharpe ratio) landed in the top decile of the category over both periods. The fund has similarly outperformed since July 2021, when Moran and Pozen’s shared tenure as lead managers began. Over the period, the fund’s 6.2% return bested the category average of 4.3% and the index’s 2.9%.
Holding more equity than peers has aided the fund’s performance. The fund’s average equity allocation of 65% over the trailing 10-year period was greater than the typical peer’s 57%. The managers do not make top-down calls between stocks and bonds, which is hard to get consistently right, and the discipline to keep the fund’s allocation around its 65% equity/35% bond strategic weightings has benefited long-term shareholders.
The fund notched strong results in 2024. Its 14.9% gain bested 83% of category rivals and trounced the category index’s 8.3% return. As of the December 2024 portfolio, six of the top 10 equity holdings were members of the Magnificent Seven, which experienced another year of robust returns and contributed to outperformance over peers. The fund’s large-cap bias also helped as large-cap stocks again bettered mid- and small-cap stocks.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States