10 min read
Economic Moat Ratings: How Competitive Advantages Stack Up
Key Takeaways
Morningstar considers five factors when evaluating a company's moat: intangible assets, switching costs, network effect, cost advantage, and efficient scale.
- For the best long-term results, our analysts believe that combining a moat with an undervalued stock has a track record of outperformance.
While businesses with sustainable competitive advantages are rare, history shows that some companies have been able to withstand the onslaught of competition—often becoming wealth-compounding machines.
The Morningstar Economic Moat Rating refers to how likely a company is to keep competitors at bay for an extended period. Morningstar has developed the concept into a comprehensive framework that can be applied consistently across a broad, global list of companies.
Our comprehensive guide shares actionable tips, resources, and tools to help you support clients and make more informed investing decisions.
What Is An Economic Moat?
A company with an economic moat has a structural competitive advantage that allows it to sustain economic profits over a long period of time. As a result, these companies are more likely to create value for themselves and their shareholders, which can lead to providing funds and portfolios that align with client needs.
How Have Wide-Moat Stocks Performed?
The Morningstar Wide Moat Composite Index shows that wide-moat stocks returned 19.68% in 2025, beating the broader Morningstar US Market Index, which returned. Wide-moat stocks have also tended to see smaller price swings than no-moat stocks.
Five Sources of Economic Moats
We look for five sources of structural competitive advantage when evaluating companies.
Intangible assets
Unique features such as patents, brands, and regulatory licenses can prevent competitors from duplicating a company’s products or allow the company to charge higher prices.
For example, patents protect the excess returns of many pharmaceutical manufacturers, such as Novartis NVS. When patents expire, generic competition can quickly push drug prices down 80% or more.
Switching costs
If it’s too expensive to stop using a company’s products, customers are less likely to make the switch. But price isn’t the only determinant of switching costs—we also consider factors such as risk, hassle, and psychology.
Consider HR software provider like Workday WDAY. Every employee is trained on the software, and the client’s processes are integrated in this system, indicating that a switch would be time-consuming and costly.
Network effect
The network effect occurs when the value of a company’s service increases for consumers, suppliers, and developers as more people use the service.
The more consumers who use Visa V credit cards, for instance, the more attractive that payment network becomes for merchants, which makes it more attractive for consumers, and so on.
Cost advantage
Firms that can provide goods or services at a lower cost can undercut their rivals on price or sell at the same price as rivals but achieve a fatter profit margin.
For example, as the largest restaurant brand in the world, McDonalds MCD can procure food and paper more cost effectively than its smaller peers. That’s an edge that we don’t expect to ease over the next few decades.
Efficient scale
This dynamic typically applies to firms that service a market of limited size, in which potential competitors have little incentive to enter because doing so would lower the industry’s returns below the cost of capital.
Let’s take a railroad company like Union Pacific UNP. New entrants have little incentive to enter the railroad market because of the sizable upfront infrastructure costs. Plus, they run the risk of creating excess capacity with limited demand, giving Union Pacific the ability to maintain its size and position in the railroad industry.
How Does Morningstar Assign Moat Ratings?
Through fundamental research, Morningstar equity analysts determine if a company holds one or more competitive advantages and whether they will result in excess returns for an extended period.
Specifically, a committee of about 20 experienced analysts spanning sectors and geographies considers the five qualitative factors outlined above to assign ratings.
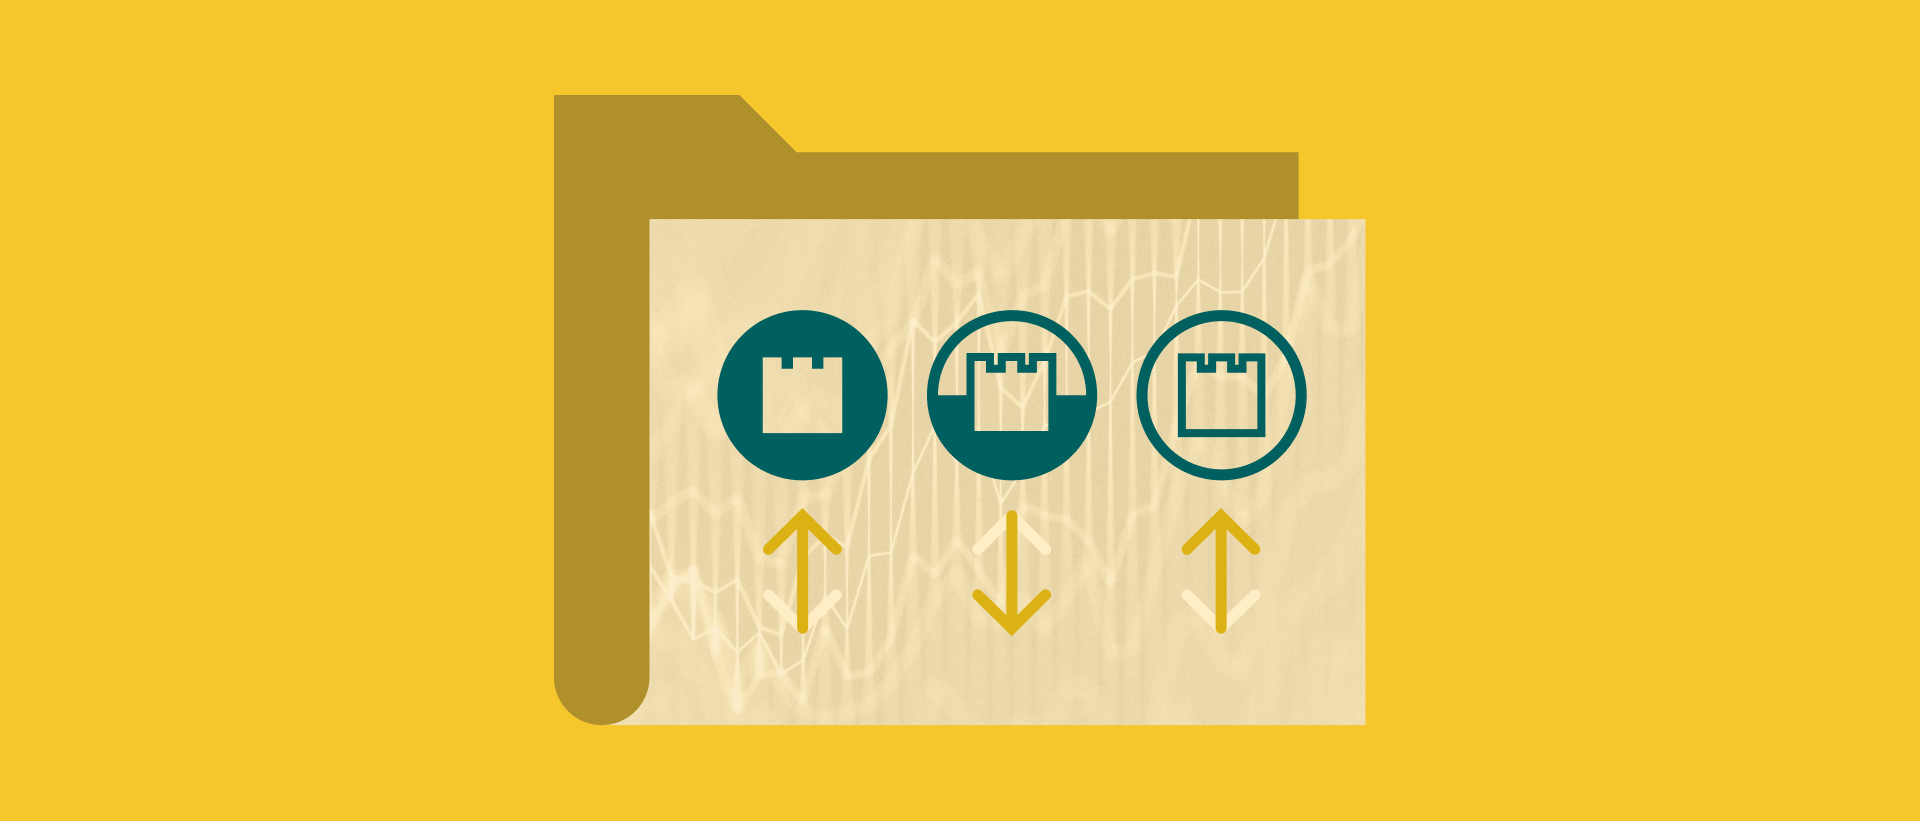
Wide moat: A company with a strong defense against rivals that we expect to last 20 years or more.
Narrow moat: A company that should maintain a competitive edge for at least 10 years.
No moat: A company without any enduring competitive advantages. Just because a company boasts a well-known brand or has existed for a long time doesn’t mean it has an economic moat.
The Role of Attractive Valuations
Even the highest-quality company could turn out to be a value-destructive investment if it’s purchased at an excessive price. Morningstar subscribes to a long-term valuation-driven investment approach, which weighs a business’ intrinsic value relative to its market price. While price and value can become disconnected in the short term, they should converge over the long term.
Our economic moat analysis and fair value estimates are also inextricably linked. Economic profits should persist longer for companies with wide moats than those without, resulting in higher valuations.
Analyzing estimated fair value
At the heart of Morningstar’s valuation methodology is a detailed projection of a company’s future cash flows based on fundamental research by equity analysts. Morningstar believes that analyzing valuation through discounted cash flows is the best way to view cyclical companies, high-growth firms, or companies expected to generate negative earnings over the next few years.
The Morningstar discounted cash flow model expresses our long-term assessments of a firm’s competitive advantage and its impact on cash flows well into the future. It’s divided into three distinct stages:
Explicit Forecasts: In this stage lasting five or 10 years, analysts make full financial statement forecasts, including items such as revenue, profit margins, and tax rates. Based on these projections, we calculate earnings before interest, after taxes, or EBI, and net new investment to derive our annual free cash flow forecast.
Value of the moat: The second stage reflects how long economic profits should persist before a company’s returns on new invested capital, or RONIC, fall to its cost of capital. During this period that can last up to 15 years, we forecast cash flows using four assumptions: an average growth rate for EBI over the period, a normalized investment rate, average RONIC, and the number of years until perpetuity, when new invested capital no longer delivers economic profits.
Perpetuity: Once a company’s marginal return on invested capital hits its cost of capital, we calculate a continuing value, using a standard perpetuity formula. At this stage, we assume that any growth or decline or investment in the business neither creates nor destroys value and that any new investment provides a return in line with estimated weighted average cost of capital.
Moat Changes in H1 2026
The first half of 2026 was a very active period for our moat rating changes. We upgraded 18 company moat ratings and downgraded 59, with most of the changes tied to one question: how will AI reshape competitive advantage?
While AI boosted the outlook for some businesses, particularly those providing critical infrastructure, it raised new questions for others. As a result, we removed more moat ratings than we awarded during the period.
Of the 132 companies reviewed for AI-related impacts, most kept their existing moat ratings. Even so, we downgraded 22 wide moats (20 to narrow, two to none) and 18 narrow moats (to none from narrow). At the same time, a handful of firms emerged as potential AI beneficiaries. Crowdstrike CRWD and Cloudfare NET, for example, earned upgrades to wide-moat status due to their positioning in the infrastructure layer and their network effects.
Software Moat Downgrades Reflect Future Risk, Not Present Weakness
Many of our software downgrades weren't driven by deteriorating fundamentals. Instead, they reflect uncertainty around how AI could reshape the economics of software over the next decade.
The debate is still unresolved. AI could make software development significantly cheaper, lower barriers to entry, increase switching, and pressure traditional per-seat pricing models. On the other hand, software leaders may retain their advantages through deep domain expertise, compliance capabilities, proprietary data, customer relationships, and trusted brands.
With this outcome genuinely uncertain, our downgrades are largely based on uncertainty about future returns rather than current performance.
Cybersecurity Looks Built to Benefit from AI
Not every tech sector faces disruption from AI. In cybersecurity, AI may actually strengthen competitive positions.
As attackers gain access to more sophisticated AI tools, organizations will need even stronger defenses. At the same time, AI expands the number of potential attack surfaces and reinforces the importance of regulatory compliance, creating sustained demand for security solutions.
That’s one reason we maintained wide-moat ratings for Palo Alto Networks PANW and Fortinet FTNT, while upgrading Cloudflare and CrowdStrike to wide-moat status. We see the strongest advantages accruing to companies with large-scale security networks, deep workflow integration, proprietary data, and usage-based pricing.
CrowdStrike’s Data Advantage Gets Even Stronger in an AI World
CrowdStrike's upgrade from narrow to wide moat reflects the power of its network effect.
The company collects an enormous volume of proprietary threat data from its customer base. That data improves detection capabilities, leading to stronger security outcomes, which in turn attracts more customers and generates even more data. It's a feedback loop that's becoming increasingly difficult for competitors to replicate.
We believe AI strengthens rather than threatens this dynamic, since AI increases both the sophistication and volume of attacks (including the prospect of autonomous, always-on malicious agents), which only raises the value of CrowdStrike's structural data and scale advantages. Given its position at the infrastructure layer of the security stack, we see CrowdStrike as one of the clearest beneficiaries of AI proliferation rather than a casualty, warranting our upgrade to a wide-moat rating. Uptake of its AI security products is already translating into strong revenue growth.
Crane Earns a Wide Moat on Improved, Concentrated Portfolio
Crane's upgrade to a wide moat reflects both a stronger business mix and a more focused portfolio.
For years, the company's aerospace and advanced technologies segment demonstrated wide-moat characteristics. More recently, its process flow technologies business has also become more differentiated, particularly in markets such as water treatment, pharmaceuticals, chemicals, and industrial automation.
Customers in these industries place a high premium on reliability, creating meaningful switching costs and recurring aftermarket revenue opportunities. Today, roughly 45% of Crane's CR sales come from aftermarket parts and services, helping support more durable returns. The company's decision to divest its no-moat engineered materials business further strengthened the overall profile.
Credit Bureaus Lose Their Wide-Moat Statuses
We think Equifax's EFX, Exprian's EXPN, and TransUnion's TRU datasets are highly proprietary and do not face a credible threat from AI disruption.
However, past returns on invested capital have been underwhelming. Returns should improve modestly, but volumes are difficult to predict, and regulatory uncertainty remains regarding the tri-merge requirement for government-conforming mortgages. Meanwhile, Fair Isaac FICO is gaining more of the value chain as its move to a direct license model threatens credit bureau markups on scores. Taken together, those factors led us to conclude their advantages are not as durable as we previously believed.
Etsy’s Core Marketplace Remains Strong, but Its Broader Ambitions Fell Short
We downgraded our economic moat rating for Etsy ETSY from wide to narrow due to the limits of its network-effect advantage. Etsy pursued a "House of Brands" strategy to expand beyond its core marketplace, but the divestitures of Elo7 (2023), Reverb (2025), and the pending Depop sale to eBay reveal that Etsy can't extend its network effect into adjacent retail categories.
Previously, we believed Etsy could leverage its large, engaged user base to succeed in these adjacent verticals, but this unwinding proves that view wrong. Without that extensibility, we no longer believe Etsy can generate excess economic returns over a 20- year horizon, so we're pulling back to a narrow rating.
That said, we still see real strength in Etsy's core marketplace. Buyers and sellers have built a self-reinforcing, trust-based network within Etsy's handmade and hard-to-find niche: GMS has more than doubled since 2019, active buyers have grown from 46 million to 87 million, and Etsy has pushed its take rate from 16.5% to 24.2% without losing sellers. In 2024, Etsy removed roughly 1.4 million low-quality storefronts and saw no meaningful drop in sales, suggesting the trust layer is holding up. Meanwhile, well-founded rivals like Amazon Handmade and Wish, plus smaller Etsy clones, have all failed to replicate this dynamic.
While we still award Etsy a narrow moat, we now see that moat as confined to its original craft vertical rather than something it can extend across e-commerce broadly.
Baidu’s Search Advantage Is Fading
Baidu's downgrade from wide moat to no moat reflects what we see as a long-term erosion of its position in online search.
Traditional search still made up 49% of revenue in Q3 2025, but that segment fell 18% in the quarter, and Baidu BIDU stopped disclosing it by Q4. We think Baidu will keep losing share to other apps and generative AI chatbots over the next decade, so we don't see a moat in the core search business.
Current trends are not in its favor either. Chinese users are searching more within other apps — social networking, short video, and platforms like Little Red Book, whose daily search volume roughly doubled between 2023 and 2024.
Baidu's user growth is also lagging peers, and its own AI app ranks far behind Douyin's Doubao and DeepSeek in monthly active users. As more content and data get locked inside individual vertical apps, Baidu's search results become less comprehensive, which drives a vicious cycle of declining usage and relevance.
JD.com Faces Growing Competitive Pressure
We downgraded JD's JD moat from wide to none, driven mainly by intensifying competition in China's online shopping market.
Douyin and PDD have taken meaningful gross merchandise value share from JD by offering fundamentally different shopping formats. Douyin built its business on short video and livestreaming e-commerce, which drives impulse purchases in discretionary and low-ticket categories, and it's now expanding into shelf-based, search-driven e-commerce too, putting it in more direct competition with JD's core model. PDD, meanwhile, wins on price for consumers who don't need JD's fast delivery, and it already draws a larger monthly active user base than JD.
We also see JD's traditional advantage in speed and quality eroding to on-demand delivery platforms, which now deliver in an average of 38 minutes and are increasingly capturing impulse categories (alcohol, snacks, urgent needs) and pushing into electronics and appliances.
Go Deeper With the Direct Platform
Get equity insights where, when, and how you need them with Morningstar Direct Platform. Our applications now draw from unified data, analytics, and research—helping you make better, informed portfolio decisions.
Explore even more exclusive data on more than 20,000 equities and build portfolios that fit client needs.