9 min read
Telecommunications Industry in Europe: Key Trends and Investment Opportunities in Q3 2026
Regulatory fragmentation, network duplication, and intense competition keep returns below the cost of capital.
European telecoms remain structurally undersized compared with global competitors, and our latest analysis argues the sector needs a regulatory overhaul. New EU merger guidelines could ease the path to consolidation, but the outcome hinges on how regulators apply them, and incumbents in most mobile markets are expected to cede share to newer, low-cost providers.
Morningstar’s European Telecommunications Industry report finds that European telecoms do not generate returns above their cost of capital on an aggregated basis, with fragmented regulation, duplicated networks, and intense competition continuing to weigh on the sector. Investors should focus on cost reductions and leaders with strong home market presence. Download the free report.
How Have European Telecom Stocks Performed?
European communication services stocks took 25 years to surpass their dotcom-era peak, as weak growth, aggressive competition, and stringent regulation weighed on share prices.
What are the Biggest Themes in European Telecoms?
European Telecoms Have a Monetization Problem
European telecoms have suboptimal scale and pricing compared with their international counterparts, weighing on profitability and returns on invested capital. Europe’s average mobile prices are one-third and one-half of those in the US and Asian peers, while the regulatory environment is more complex, adding administrative burdens and inefficiencies.
National regulators focus more on benefiting consumers than shareholders, forcing the entrance of new players that bring intense pricing pressure to the market. The European Commission rarely allows cross-border or national mergers without remedies.
The Regulatory Environment Is Fragmented
The European regulatory landscape is complex. Firms must comply with too many layers of regulation, including European, national, and sector-specific.
For two decades, pan-European telecoms such as Telefonica, Orange, and Vodafone have realized few cross-border efficiencies, given that networks can be at different stages of development across countries, separate spectrum auctions, and national regulators’ differing views on key matters. The regulatory landscape needs to be turned on its head to provide a more compelling framework that favors shareholder value creation.
Network Overbuilding Erodes Efficient Scale
Europe has too much redundant infrastructure. Rather than reaping the benefits and cost savings of sharing mobile infrastructure, European operators have for years built duplicate infrastructure, resulting in high costs and operational complexity.
On the broadband front, network overbuilding hurts the internal rates of return of new fiber projects. The stability of returns is also fragile: it only takes a new low-cost player entering a market and competing on price to reset returns on invested capital to a lower, permanent base.
Consumer Broadband and Mobile Is European Telecoms’ Main Business
European telecom companies differ in their reporting standards, with some focusing on the mobile-versus-fixed breakdown while others emphasize the consumer/residential segment versus the enterprise/business segment.
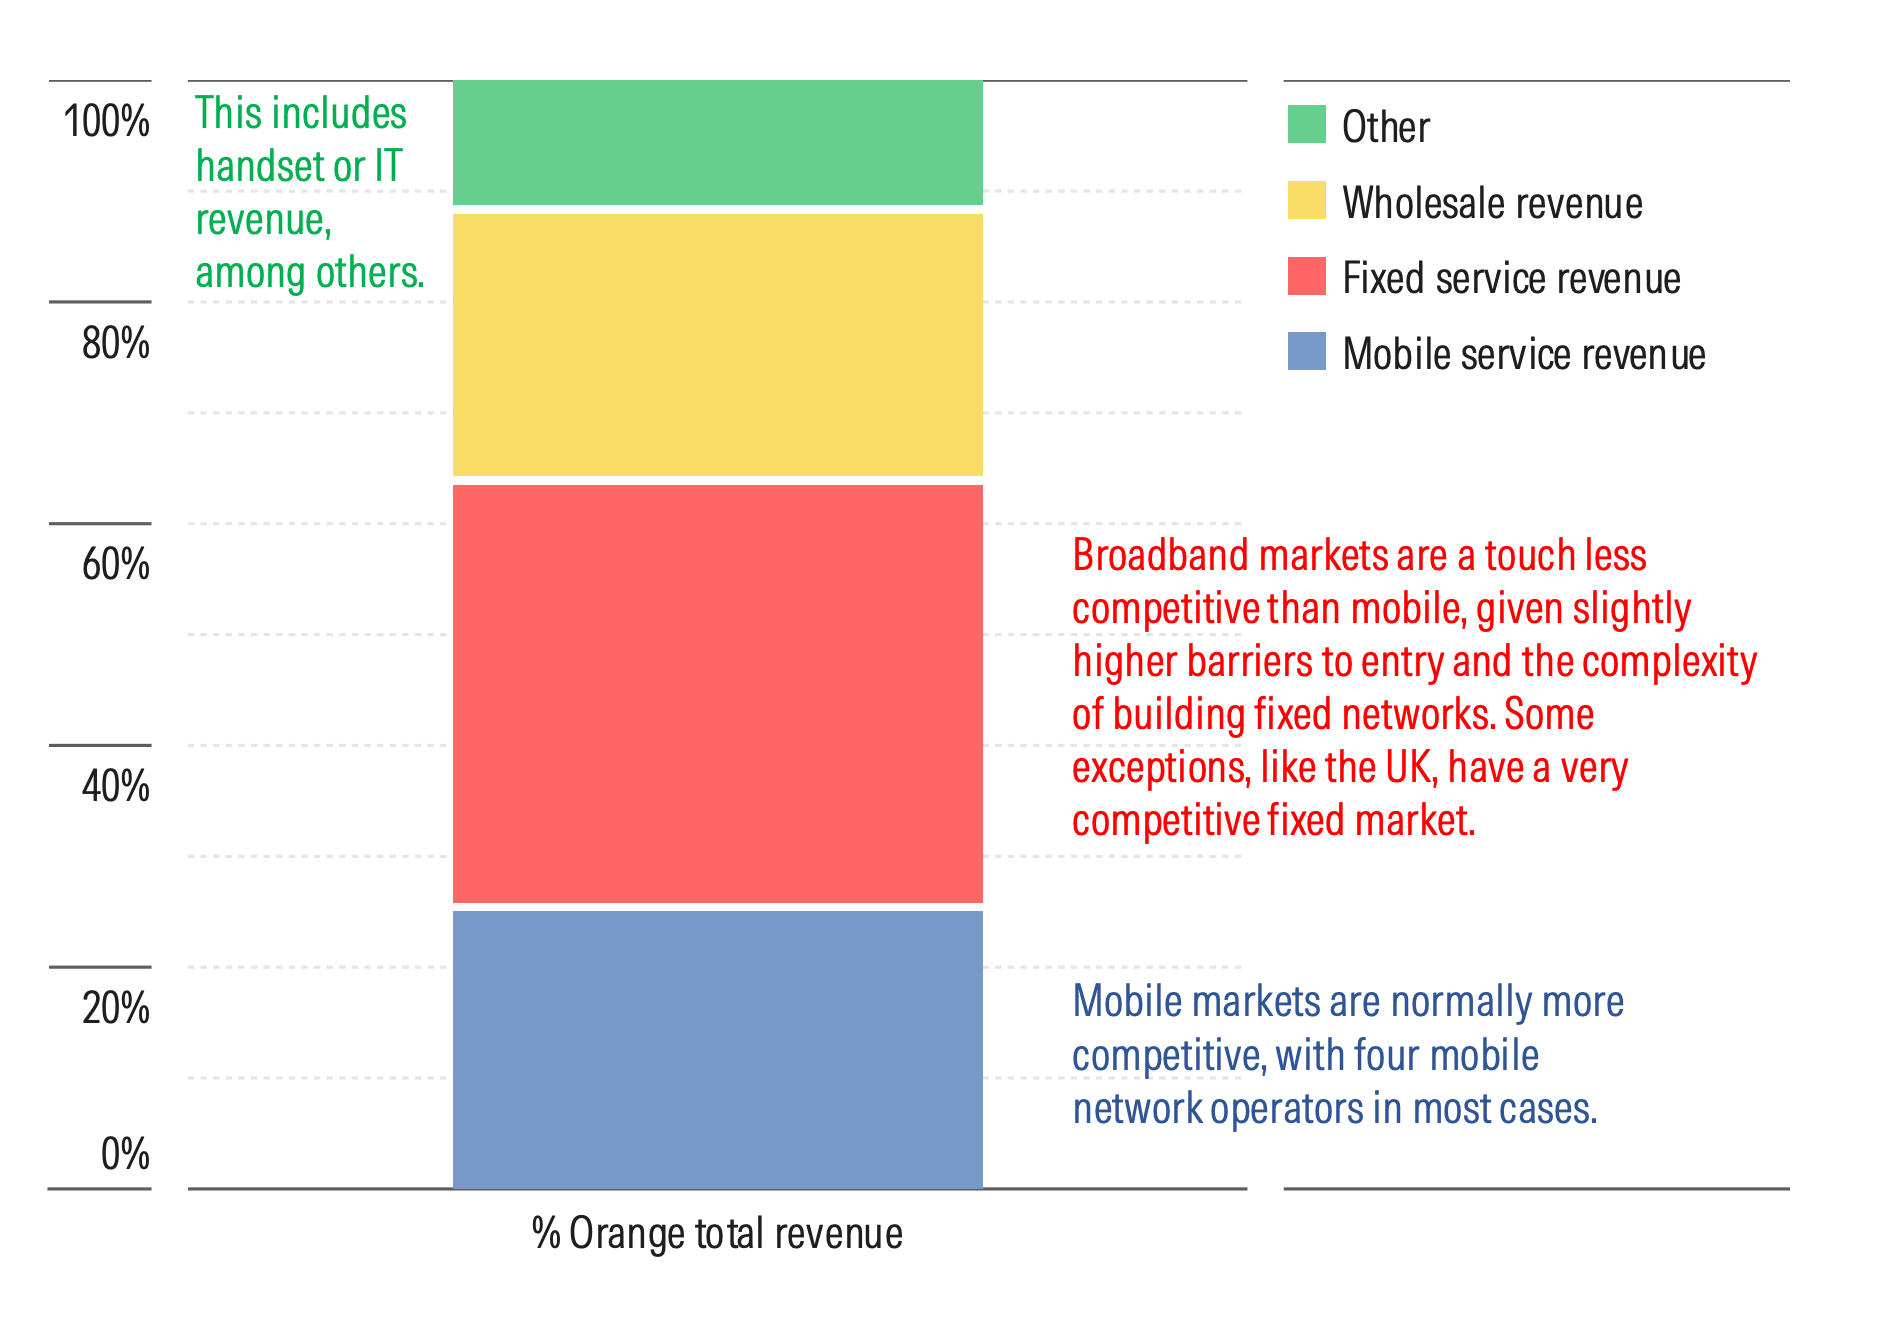
As a rule of thumb, 60% of the revenue pile typically comes from either 1) mobile and fixed-line services or 2) the consumer/residential market. The remaining 40% of revenue comes from wholesale, business clients, handset sales, and IT services.
Orange Derives 60% of Its Revenue From Mobile and Fixed Services
This Roughly Matches KPN’s 60% of Revenue From Its Consumer Segment
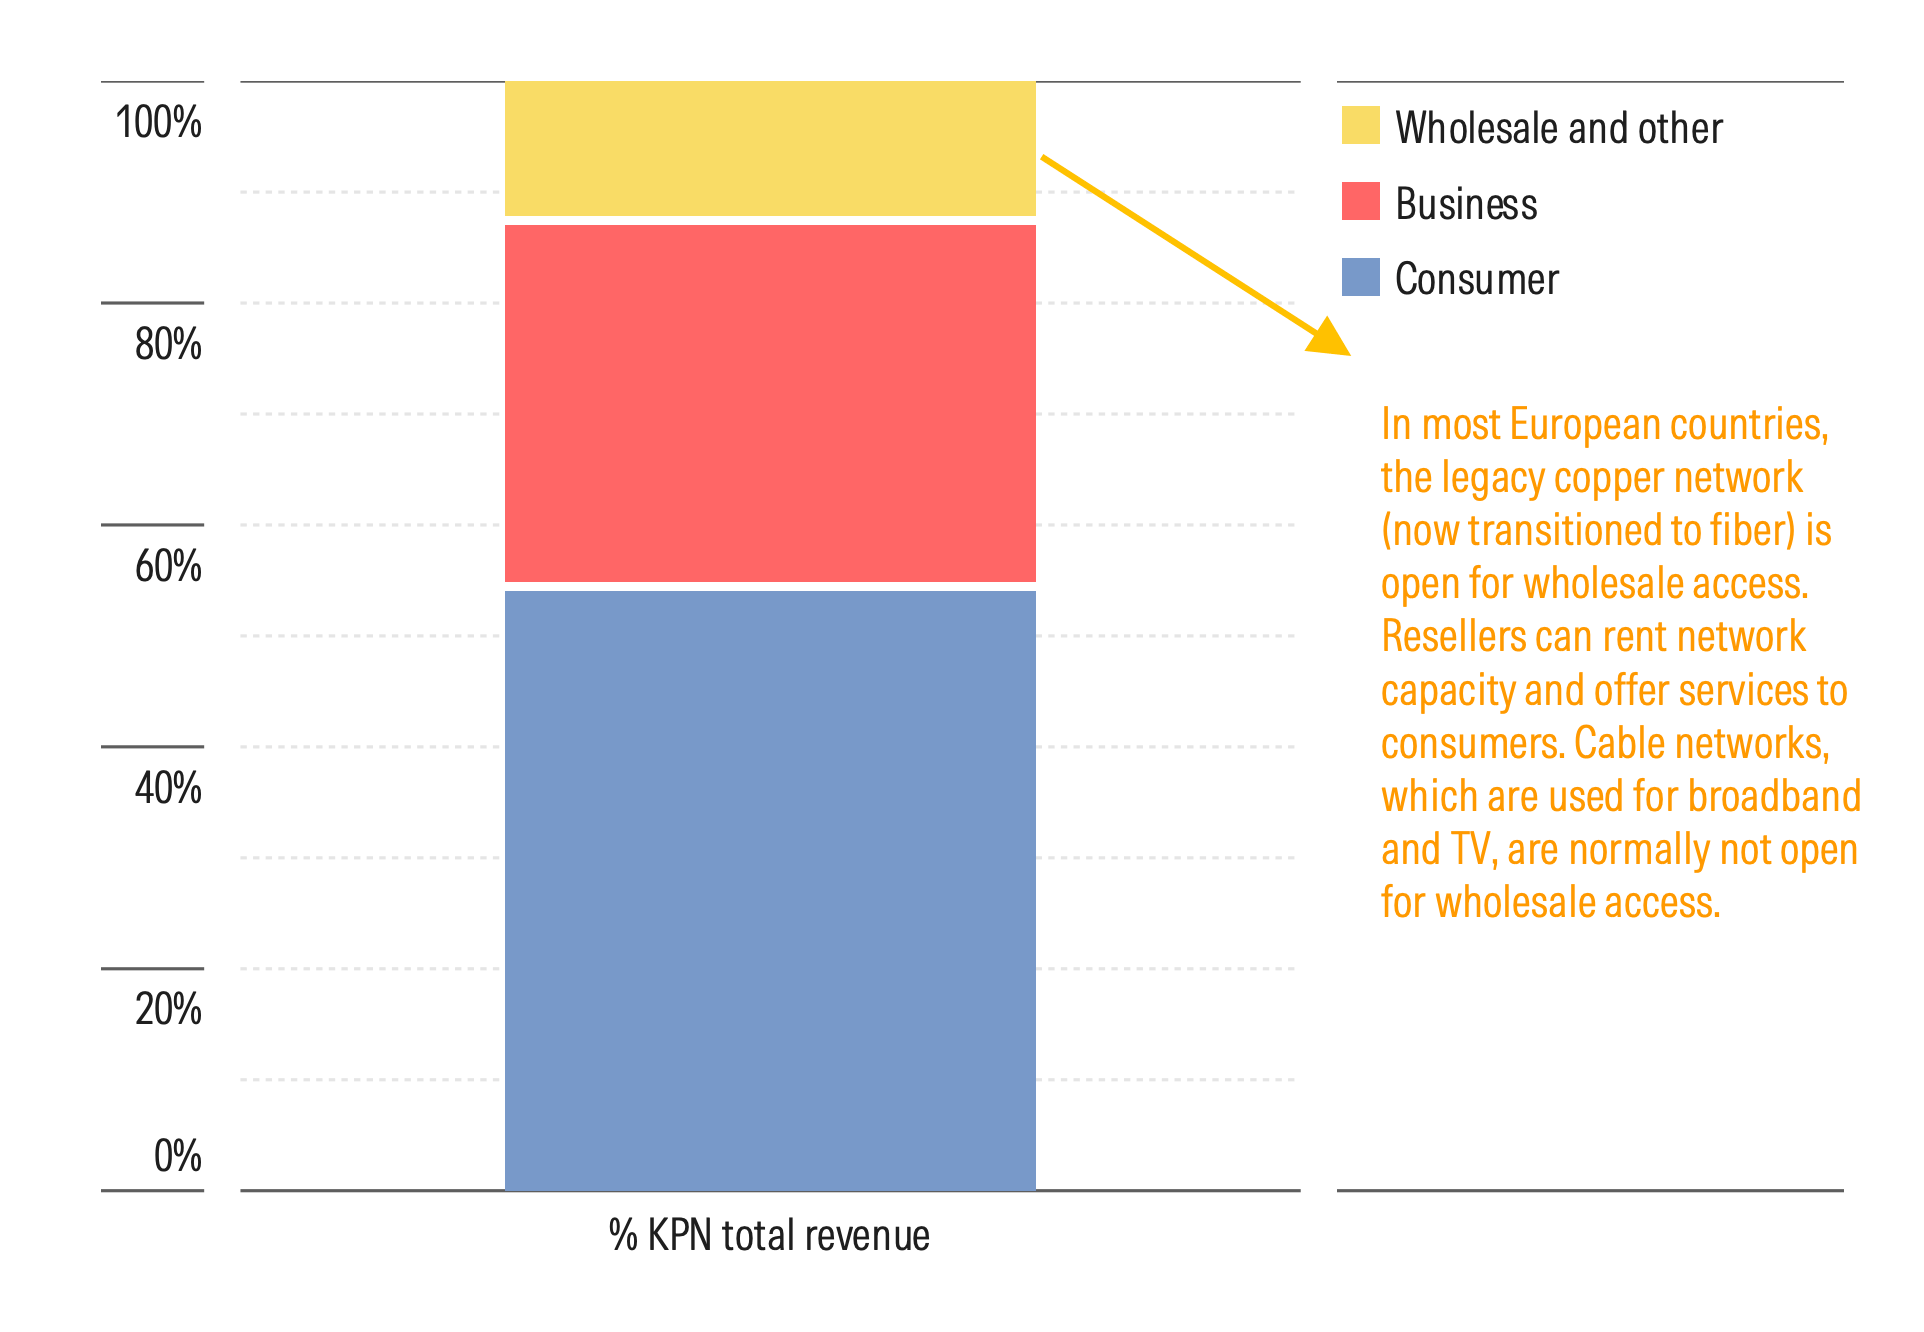
Source: Morningstar, company filings. The financial statements of Orange and KPN have been used as examples.
Moat Ratings and Sources: Only Three European Telecoms Enjoy Narrow Moats
Seventy-five percent of our European telecom coverage, or 10 out of 13, have a no-moat rating, with only three firms being narrow-moat (Deutsche Telekom, KPN, and Telenor). The efficient-scale moat source has disappeared for most European telecoms due to network duplication.
The regulatory environment is complex, with too many layers and little cross-border synergies for operators. Aggressive competition from low-cost players is also a significant barrier to maintaining a moat.
10 Out of 13 European Telecoms Have a No-Moat Rating
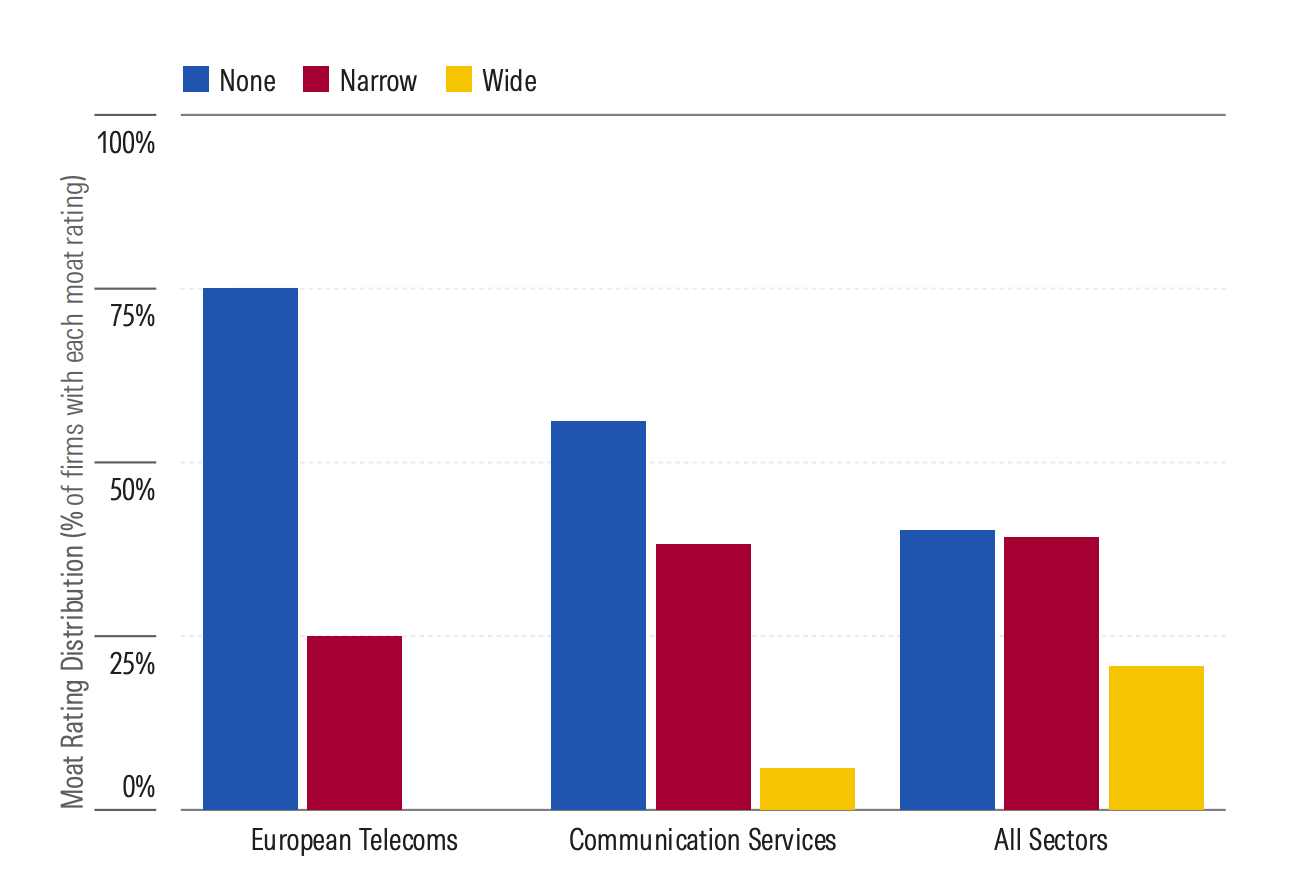
Source: Morningstar.
Europe’s Inability to Monetize Drives High Capital Intensity
European telecoms capital intensity is 30% higher than the US/Japan/South Korea average. However, Europe spends 40% less than the US and Japan on a per capita basis, and roughly the same as South Korea.
These two factors can coexist because Europe generates less revenue per capita than US/Japan/South Korea. In other words, Europe has too much network infrastructure for the revenue it generates. Market fragmentation and unfavorable regulations are the main drags.
High-Single-Digit Dividend Yields Are Nice… While They Last
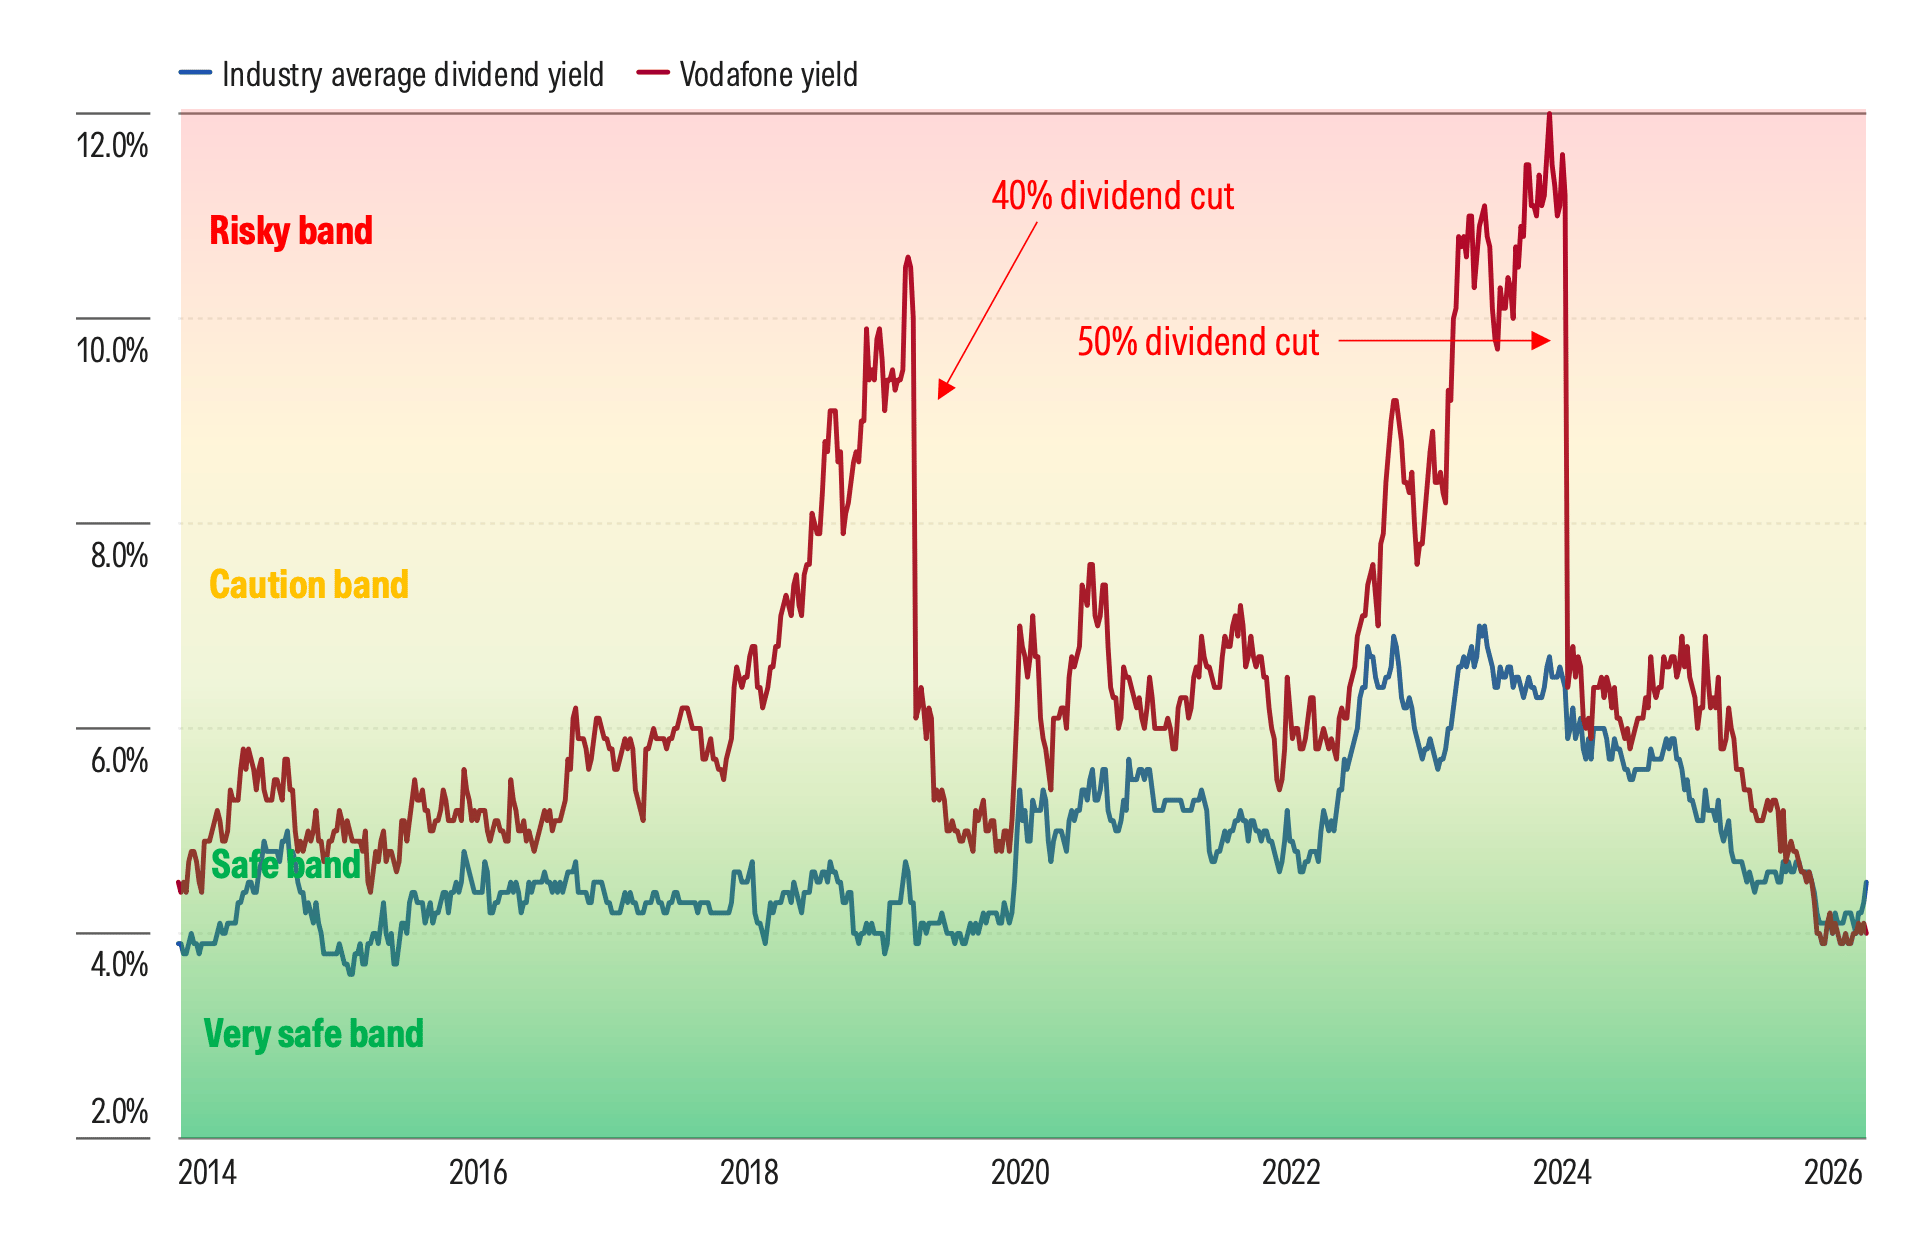
Telecoms’ high dividend yields can seduce income investors. Many firms screen well: you can own a relatively stable business, trading at a low EV/EBITDA multiple that offers a high-single-digit dividend yield.
Telecom firms have absolute dividend policies rather than payout ratio policies, which also provides visibility on future income. But when dividend yields jump above 8%, the risk of a dividend cut becomes meaningful, and investors need to lower their expectations.
It occurred with Vodafone in April 2024 and with Proximus in January 2023 (50% cut each). When Telefonica’s yield was almost 12% in 2021, management didn’t cut it but pivoted to a scrip dividend policy, which is not real remuneration as it only dilutes shareholders.
We recommend investors buy yields of well-managed companies in the safer area of 3%-6% with the option of dividend growth. DT, KPN, or Tele 2 are perfect examples of this, and they tend to be our preferred dividend plays.
Source: Morningstar, PitchBook.
Investors Should Prioritize Dollar-Growing Dividends Instead of Chasing High Yields
In our view, Deutsche Telekom and Vodafone offer the best absolute dividend growth in the next five years. Deutsche Telekom, because T-Mobile US acts as its main growth engine, with the US offering greater economies of scale, healthier pricing than European markets, which enables mid-single-digit EBITDAal growth.
Vodafone’s dividend can grow from here because the firm did a 50% cut in 2024, rebasing it to a lower base. We expect Vodafone will enable an ambitious cost program thanks to the arrival of Xavier Niel as its main shareholder, which should support great EBITDAaL and cash flow generation.
Tele2 and KPN are third and fourth. Both count with an Exemplary Capital Allocation rating, with Net Debt to EBITDAaL below 2.5 times, consistent cost-cutting, and strong positions in their home markets.
While we estimate Swisscom’s dividend will grow, we have less certainty overall as the company is still integrating Vodafone Italia in a market that remains highly competitive and where Telecom Italia and Iliad are also trying to defend or gain market share.
European Telecoms Outlook
European telecoms are showing encouraging signs of improvement. Regulatory sentiment is becoming more constructive, competition is easing in certain markets, and consolidation is back on the agenda.
However, the sector's long-term structural challenges remain intact. Revenue growth is still difficult to achieve, and most stocks now trade close to fair value.
For investors and advisors, selectivity remains critical. Companies with disciplined capital allocation, resilient market positions, and sustainable dividend growth continue to offer the most attractive opportunities.
Morningstar covers a broad universe of European equities. Our investment analysis application includes up-to-date price-to-fair-value estimates, EV/EBITDA ratios, dividend yields, and one-year return data.