
Why We Think the Market’s Outlook for Housing Stocks Is Overly Bearish
How the US housing market is coping with Trump’s immigration and tariff changes.

Housing-related stocks—homebuilders, home improvement retailers, and building product manufacturers—have underperformed the broader market since President Donald Trump’s election, signaling the market’s fears that his immigration policies will worsen the construction labor shortage and that tariffs will reignite inflation.
This has created uncertainty for a US housing market already coping with poor affordability.
However, we think the market’s outlook for housing stocks is overly bearish, as we’ve detailed in our recent report, “US Housing Insights: Immigration and Tariff Policy.”
Most building materials are manufactured in the US, while others are currently exempt from Trump’s tariffs. We also have muted expectations for an impact from lower immigration. A greater concern is tariff policy leading to much lower consumer confidence and perhaps triggering a recession. That scenario would not be good for the homebuilding industry.
Key Takeaways on the US Housing Market
- We estimate tariffs on imports from China, Canada, and Mexico will increase construction costs by a low-single-digit percentage. Goods compliant with the United States-Mexico-Canada Agreement are currently exempt from tariffs, and that estimate assumes USMCA-compliant goods and semiconductors remain exempt. (Without those exemptions, the estimated increase could move to mid-single-digit. )
- We anticipate that homebuilders and building products retailers will push back on price increases and that building product manufacturers and their suppliers will absorb some costs rather than passing them entirely to the consumer.
- We think mass deportations are unlikely, and we anticipate moderate immigration tightening.
- While elevated uncertainty may weigh on near-term new home production, over the longer term, we still see a runway for greater headship and homeownership rates among younger Americans, especially if mortgage rates ease as we expect. Over the next 10 years, we forecast homebuilders will start roughly 1.1 million single-family homes annually, on average.
Tariffs: US Construction Value Chain Navigating a Fluid US Trade Policy
Trump has issued 25% tariffs on imports from Canada and Mexico and a 145% tariff on imports from China. Product-specific tariffs have also been announced, including a 25% tariff on steel imports and a hike in the tariff on aluminum imports to 25% from 10%. These tariffs will apply to imports from all countries, including Canada and Mexico. Goods compliant with the US-Mexico-Canada Agreement are currently exempt from tariffs.
Even before tariffs were implemented, players throughout the US construction value chain—including building product manufacturers and distributors, homebuilders, and retailers—had begun acting to defend profit margins amid uncertain US trade relations.
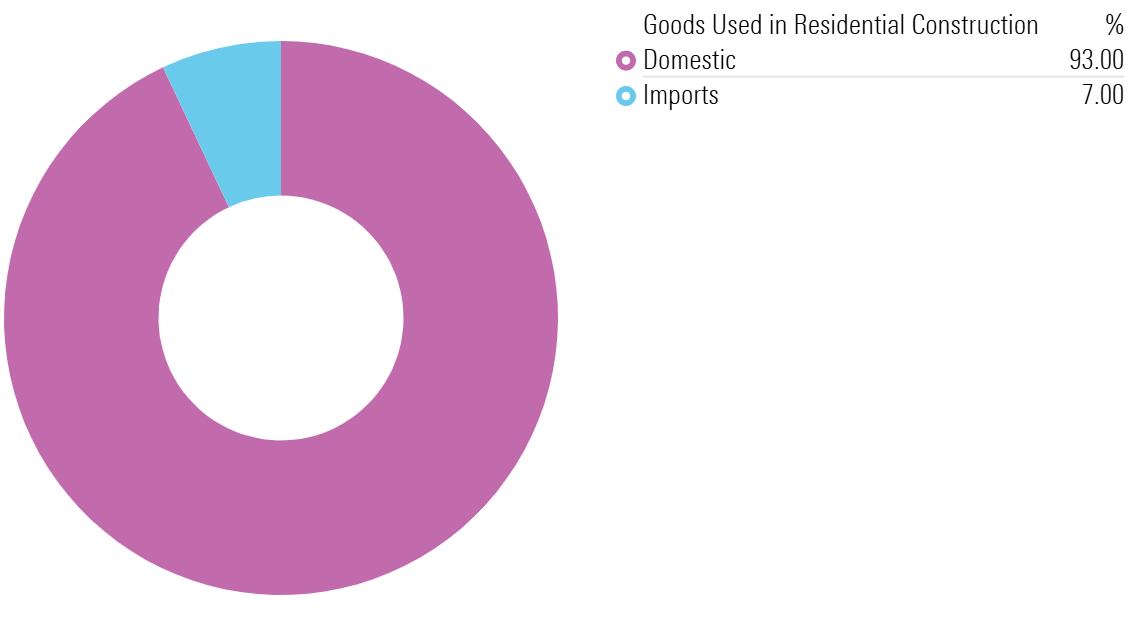
However, the value chain’s overall exposure to China, Canada, Mexico, and other countries is limited and varies by company. In fact, according to the National Association of Homebuilders, just $13 billion (approximately 7%) of such goods were imported in 2023. The largest distributors and retailers have a diverse supplier base that provides for a flexible product strategy.
Construction Costs and Materials for a New Single-Family Home
In a typical new single-family home, 15 structure components account for 75% of total construction costs, including material, labor, and other expenses. Materials used for framing (lumber) and HVAC installation (often an air conditioner and furnace) tend to represent a greater portion of the total construction cost for these structures—and a substantial portion of these components’ manufacturing is done in Canada and Mexico. So, if the tariffs on Canada and Mexico were imposed without exemptions, we believe these two structure components would be the key drivers behind higher construction costs.
We estimate that the cost of constructing a single-family home could increase by a low-single-digit percentage if the tariffs on imports from China, Mexico, and Canada remain in effect for an extended period. As mentioned, USMCA-compliant goods are currently exempt from tariffs. We believe this exemption applies to HVAC equipment and many other building products manufactured in Mexico.
Most Building Products Are Manufactured Domestically
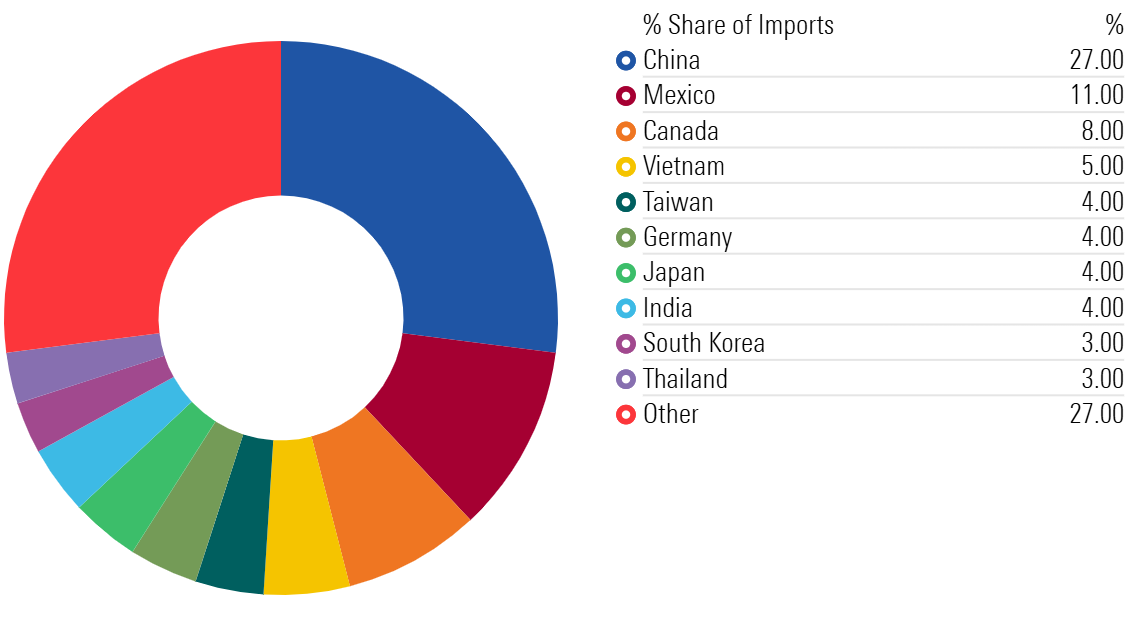
China, Mexico, and Canada Account for Nearly Half of Imported Building Products
On the other hand, we think China tariffs will have a less impactful mark on construction costs owing to the lower value content of oft-imported products—for example, appliances account for less than 2% of construction costs. At such high tariff levels, we think the supply chains suppliers would look for substitutes for China products, which also would help lower that impact. The value chain had already reduced its dependence on China after it suffered severe supply chain disruptions during the covid pandemic.
A low-single-digit percentage increase is not inconsequential, given already poor housing affordability. However, we believe homebuilders and building products retailers will push back on price increases and that building product manufacturers and their suppliers will absorb some of these costs, rather than passing them entirely to the consumer.
During fourth-quarter earnings calls, most manufacturers said they’d fully offset tariffs with price increases. However, during its first-quarter call, Lennar LEN (the second-largest US homebuilder) said it would push back on building material price increases.
As we highlighted in our report, members of the value chain (homebuilders, retailers, distributors, and manufacturers) all still have higher profit margins than before the covid pandemic, so we see room to absorb higher costs.
Immigration Policies Expected to Have Little Effect on Construction Labor Supply
The general message from public homebuilder management teams during fourth-quarter earnings calls was that deportations had not been an issue for the industry so far.
Morningstar sees mass deportations as unlikely and instead expects moderate immigration tightening during the Trump administration. As explained in our fourth-quarter 2024 economic outlook report, Morningstar projects US population growth of 0.41% over 2024-28, lower than the 0.70% average from 2020-24. This is due in part to a lower average net migration rate of 0.27% over 2024-28, down from an average of 0.42% during the 2010s.
Morningstar Senior US Economist Preston Caldwell notes that there wasn’t a large decrease in immigration during Trump’s first term, owing to legislative obstacles, legal challenges, and obstruction from state and local governments; he expects many of these challenges will persist during Trump’s second term.
Even so, stronger border enforcement, deportations of those who already received orders to depart, and removal of protections for quasi-legal categories of immigrants should result in lower net migration over the next few years.
If our immigration outlook proves to be correct, we would expect immigration policy to be, at most, a modest headwind to construction labor supply—not an issue that the homebuilding industry couldn’t manage.
Nevertheless, a shortage of construction labor (especially skilled trades) has plagued the US construction industry for some time. While increased immigration would help, the construction industry needs to attract more native-born workers, too. On that front, greater support for trade schools and apprenticeship programs would help address the issue.
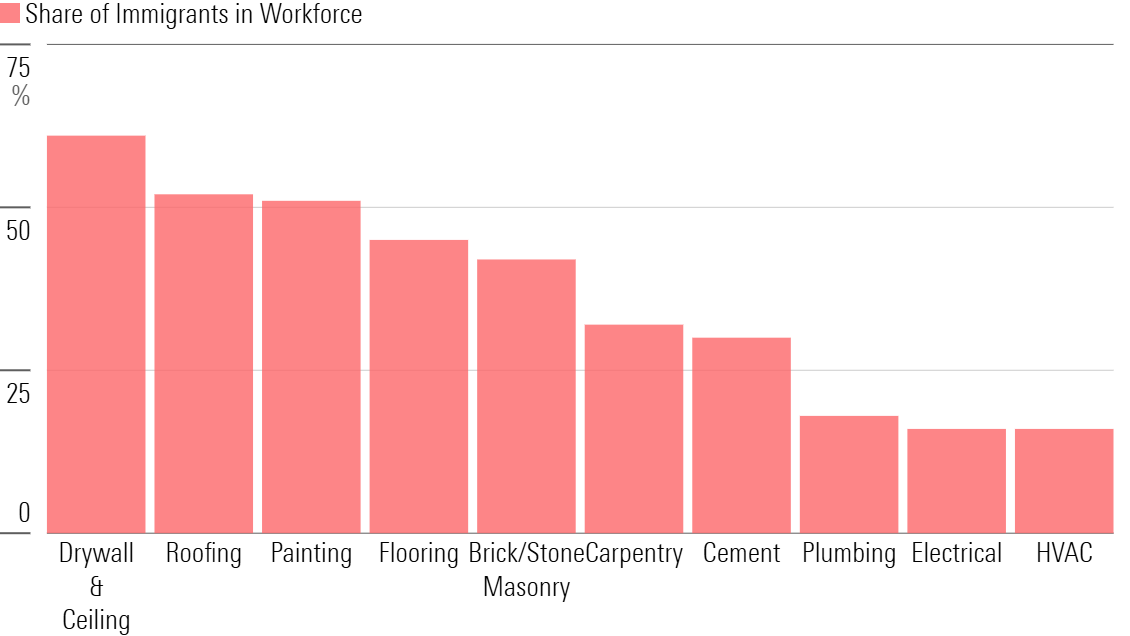
Immigrants Make Up a Sizable Portion of the Construction Labor Source, Especially Less-Skilled Trades
Morningstar’s population forecast assumes population growth from net migration will normalize to near 0.4% annually over 2029-34, and the total population will grow slightly faster than that (approximately 0.5%) over that same period. For perspective, without any immigration, we estimate the US population would begin to decline as soon as the next decade due to below-replacement-level fertility rates. In our view, a shrinking US population would be unfavorable for the residential construction industry.
We expect a larger immigrant population will place some near-term strain on an already undersupplied US housing stock, especially for multifamily units. That said, multifamily construction during 2021-23 reached levels last seen during the late 1980s, and the construction backlog for multifamily units remains elevated. However, we suspect these units skew more toward higher-end units that wouldn’t accommodate cost-burdened immigrants. Nevertheless, our residential construction forecast assumes the housing stock shortfall will gradually be addressed over the next decade (albeit not fully addressed), and we project total annual housing starts will average approximately 1.5 million units (1.1 million single-family and 0.4 million multifamily) over the next 10 years.
This article was compiled by Tori Brovet.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States