
The Bright Spot for Actively Managed Funds Amid a Dire Picture
Robust inflows for active bond strategies align with better odds for outperformance.
Reviled as un-American when it debuted 50 years ago, passive fund investing has increasingly become the country’s preferred choice over actively managed strategies. Its popularity looks different across the stock and bond asset classes, though, and that’s likely a pointer to where investors think they have the best chance of success in opting for active management.
Investing basics: what is active and passive investing?
A Record Year for Passive Investing
Last year was a record haul for passive US open-end and exchange-traded funds, overall. The $951 billion of new money into passive strategies was their largest calendar-year inflow and stood in contrast to the nearly $187 billion pulled out of active funds. The net difference between passive and active thus exceeded $1 trillion in 2025.
That large swing added to passive investing’s market share edge. Passive funds’ $19.4 trillion in assets at year-end 2025 represented a 55% share of the US funds market. Active funds’ $16.0 trillion in assets is still a huge sum, but it is shrinking relative to passive strategies.
A Dire Picture for Active Equity Funds
The picture is dire for active equity fund flows. They experienced more than a half trillion dollars of outflows in 2025, part of a $3.2 trillion exodus over the past decade. That dropped their market share from 58% in 2016 to 37% today.
International active equity funds, which include global strategies, have fared a little better than their domestic counterparts in terms of their share of total assets managed. Still, passive international equity funds’ share of the market overtook active strategies’ share in 2025, making up 52% of the market at year-end from about 48% to start the year.
Fixed-Income Funds as a Bright Spot for Active Management
Granted, active fixed-income funds have been subject to the same broad trends. Their market share relative to passive bond strategies fell from 73% in 2016 to 61% today. Flows in 2025 contributed to that falling share, with passive funds taking in $303 billion in new money, versus $237 billion for active bond strategies.
But active bond funds remain a bright spot relative to active equity strategies. Although their market share is also declining relative to that of passive competitors, the rate is slower. Active bond funds’ overall share is still well above 50%, and in categories like municipal bond, it remains dominant, where active strategies have 86% of the assets.
Annual flow comparisons paint a positive picture as well. Whereas active equity funds did not have a single year of inflows over the past decade, active bond strategies saw outflows in just two (2018 and 2022), with substantial outflows only in 2022.
Plus, active bond strategies’ $237 billion haul in 2025, among their top calendar-year figures on record, undercounted investors’ preference for active bond strategies. That number does not include flows into semiliquid bond strategies like interval funds or business development companies, all of which are active and have garnered substantial assets in recent years. Fixed-income interval funds, for example, had more than $80 billion in assets at year-end 2025.
Flows Align With Odds for Outperformance
Investors’ higher relative preference for active bond relative to active stock strategies aligns with odds for outperformance. With its ability to track broad benchmarks for little to no fees, passive investing has the most appeal for asset classes in which most active managers fail to beat their benchmarks. That’s much more the case for active stock than bond funds.
While numbers can shift depending on time periods or crises that favor active or passive strategies, long-run trends favor the consistency of active bond funds’ chances for success versus active stock funds’. That’s true of major market segments like core bonds and large-cap domestic stocks. Over the 25 years through December 2025, for example, the intermediate core bond active median (using the cheapest share class) beat the Bloomberg US Aggregate Bond Index in 46.8% of rolling three-year periods. Albeit less than half, that far exceeds the 6.4% success rate versus the S&P 500 for the active large-blend median (also using the cheapest share class).
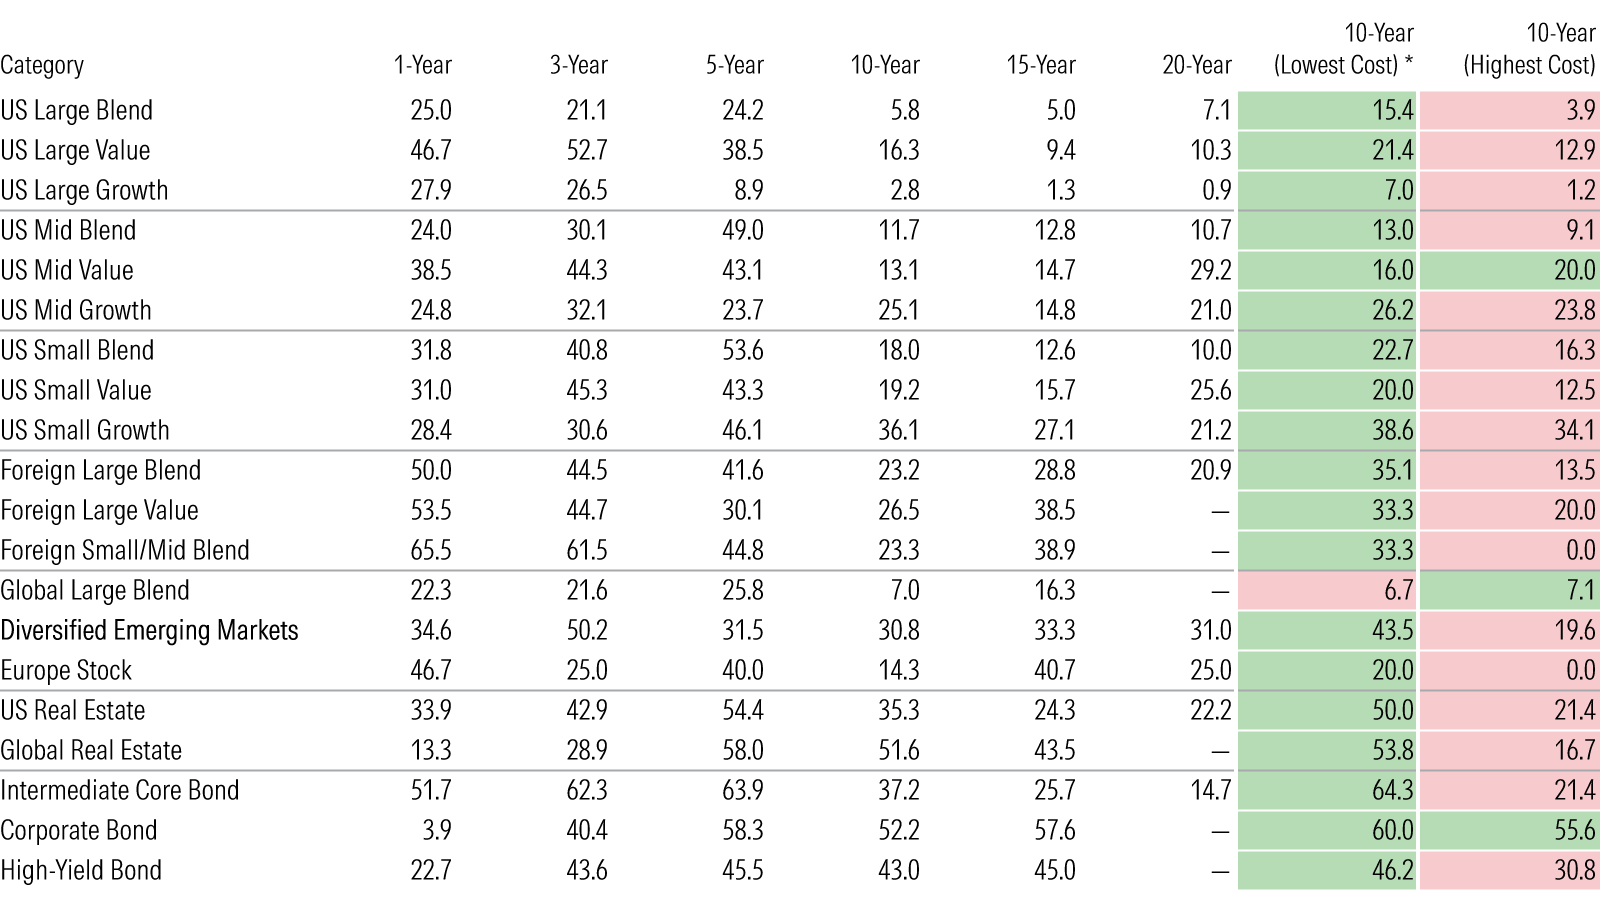
Active bond funds’ edge is also evident in more than one Morningstar Category. Our active/passive barometer research tracks fund success rates across 15 stock, two real estate, and three bond categories across major trailing periods. The highest success rate percentages over the past decade through June 2025 for the lowest-cost stock funds was 43.5% for diversified emerging markets. In contrast, success rates for cheap intermediate core bond and corporate bond active funds exceeded 60% over the same 10-year period, while high-yield bond outperformance came in at 46.2%.
Active Funds’ Success Rate by Morningstar Category (%)
Recent Morningstar research has shed light on why it’s easier to make a case for fairly priced, proven active bond funds. The bond market’s makeup and indexing challenges give skilled active managers a chance to distinguish themselves. Moreover, actively managed bond funds have access to and make use of tools, asset classes, and flexibility around interest rate and credit risk exposures to gain an advantage over passive funds and their indexes.
As long as active bond managers continue to put up competitive results, the flows picture in this asset class is likely to remain a comparative bright spot.
This article references data from the Morningstar Direct US Asset Flows Commentary for December 2025. Download the report here.
The author or authors do not own shares in any securities mentioned in this article. Find out about Morningstar’s editorial policies.

 United States